Gift tax limits in 2026: how the gift tax works

 Maya KosoffMaya Kosoff is a writer, editor and content strategist based in Brooklyn, New York. She previously worked at Vanity Fair and the New York Times. In her spare time she enjoys cooking, traveling, securing a win for her recreational skeeball team, and hanging out with her cat, Carmichael.
 Krislyn ChanKrislyn is Chief Growth Officer at Keeper. At Keeper, she strives to make expert-level tax strategies that used to require a traditional CPA accessible to all. Prior to Keeper, she was at Curology, where she helped bring custom, prescription-grade skincare out of the dermatologist's office to millions of faces.

Key takeaways
- In 2026, you can give up to $19,000 per person, to as many people as you want, with no tax and no paperwork. It was also $19,000 in 2025.
- Give one person more than that and you file Form 709 by April 15, 2027. Filing doesn’t mean you owe anything.
- You only owe gift tax once your lifetime taxable gifts pass $15 million ($13.99 million in 2025). Past that, the rate is 40%.
- The giver handles gift tax. If you receive a gift, it isn’t income and you don’t report it on your tax return.
- If you’re given stock or property, you take on the giver’s cost basis, so you may owe capital gains tax when you sell.
2026 and 2025 gift tax limits
| 2026 | 2025 | |
|---|---|---|
| Annual exclusion, per person you give to | $19,000 | $19,000 |
| Married couple giving to one person | $38,000 | $38,000 |
| Gifts to a spouse who isn’t a U.S. citizen | $194,000 | $190,000 |
| Lifetime gift and estate tax exemption | $15 million | $13.99 million |
| 529 plan five-year election, per beneficiary | $95,000 | $95,000 |
| Tax rate above the lifetime exemption | 40% | 40% |
| Form 709 due date | April 15, 2027 | April 15, 2026 |
The IRS hasn’t released 2027 figures yet. Starting in 2027, the lifetime exemption rises with inflation each year under the One Big Beautiful Bill Act, which set it at $15 million for 2026 with no expiration date.
How the gift tax calculator works
| Input | What to enter |
|---|---|
| Year you gave the gift | Gift tax runs on the calendar year, so a gift on December 31 counts toward that year. |
| Marital status | Married people can split gifts with their spouse, which doubles the annual exclusion. Your income tax filing status doesn’t matter. |
| What did you give? | Cash, stock, or property is the usual choice. Tuition or medical bills paid directly, donations to charity, and gifts to a U.S. citizen spouse are tax-free at any amount. |
| Amount given to one person | Everything you gave that person during the year. Value stock and property at what they were worth the day you gave them. |
| Advanced info | The number of people you gave the same amount to, taxable gifts from past Form 709s, and whether you’re splitting the gift with your spouse. |
It shows your federal gift tax, whether you need to file Form 709, and how much lifetime exemption you have left. It doesn’t cover gifts to a non-citizen spouse, gifts to trusts, or Connecticut’s state gift tax.
Do you have to pay taxes on money gifted to you?
No. If someone gives you money or property, it isn’t taxable income, and you don’t list it on your tax return. The gift tax is the giver’s tax, and even givers almost never owe it.
Gifted stock, crypto, or property is different when you sell it. You take over the giver’s cost basis, meaning what they originally paid. Say your uncle bought stock for $5,000 and gives it to you when it’s worth $20,000. If you sell it for $22,000, your taxable gain is $17,000, not $2,000. You also inherit how long he held it, so it’s usually a long-term gain. If the stock was worth less than he paid when you got it and you sell at a loss, your loss is figured from that lower value instead. Ask the giver for their purchase records when you receive the gift.
Gifts from abroad have one extra step. If you’re a U.S. person and receive more than $100,000 in a year from a foreign individual, or more than $20,573 from a foreign company in 2026, you report it on Form 3520. You still don’t pay tax on it, but the penalty for not reporting is steep.
The annual gift tax exclusion
The annual exclusion is what keeps most gifts off the IRS’s radar. In 2026, you can give up to $19,000 to each person, and there’s no limit on how many people. You could give $19,000 each to your two kids, your niece, and a friend, $76,000 in all, and file nothing.
The limit is per person you give to, per year, and it adds up everything you give that person:
- Cash, checks, and transfers
- Paying their rent, car payment, or credit card bill
- Stock, crypto, a car, or other property, at its value that day
- Selling them something for less than it’s worth (the discount is the gift)
- Forgiving a loan you made them
One catch: the exclusion only covers gifts the person can use right away. Gifts of a “future interest,” like most gifts to a trust, don’t qualify and must go on Form 709 at any amount.
Gift splitting for married couples
Married couples get two annual exclusions, so together you can give $38,000 to each person in 2026. There are two ways to get there:
- Each of you gives $19,000. If each spouse gives from their own money, neither of you files anything.
- One of you gives $38,000 and you elect gift splitting. The IRS treats the gift as half from each of you. You have to file Form 709 to make the election, even though no tax or exemption is used, and your spouse signs a consent on it. Once you elect it, it applies to every gift either of you made to anyone that year.
Gift splitting adds up for families. A couple with three married children can give $38,000 to each child and each child’s spouse, $228,000 a year, without touching their lifetime exemptions.
The lifetime gift and estate tax exemption
Giving one person more than $19,000 doesn’t mean you pay tax. The extra is a “taxable gift,” which you report on Form 709 and subtract from your lifetime exemption: $15 million per person in 2026, or $30 million for a married couple. You only owe gift tax once your lifetime taxable gifts pass that amount.
The gift and estate tax share one exemption. If you use $2 million of it on gifts during your life, your estate has $2 million less to shelter at your death. That’s why Form 709 matters even when no tax is due: it’s the running record of how much you’ve used. Gifts already covered by the higher exemption aren’t taxed later if the exemption ever drops.
Gift tax examples
A $50,000 gift from one parent
- You give your adult child $50,000 in 2026. The first $19,000 is covered by the annual exclusion.
- The other $31,000 is a taxable gift. You file Form 709 by April 15, 2027.
- You owe $0. Your lifetime exemption drops to $14,969,000.
The same gift, split with your spouse
- Each of you is treated as giving $25,000, so $6,000 each is over the annual exclusion.
- Together, $12,000 comes off your lifetime exemptions instead of $31,000. You still file Form 709 and owe $0.
A gift past the lifetime exemption
- A single person who’s never filed Form 709 gives $16,019,000 to one person in 2026.
- After the $19,000 exclusion, $16,000,000 is taxable, which is $1,000,000 over the $15 million exemption.
- Gift tax is 40% of $1,000,000: $400,000, due with Form 709 by April 15, 2027.
Gift tax rates
The federal gift and estate tax rate schedule runs from 18% to 40%. The rates apply to your lifetime taxable gifts, starting from the first dollar, not just to the amount over the exemption. A credit then cancels the tax on everything up to $15 million.
Because the 40% bracket starts at $1 million, all the lower brackets are used up well inside the exemption. So in practice, any taxable gift past your lifetime exemption is taxed at a flat 40%.
| Lifetime taxable gifts | Rate |
|---|---|
| $0 – $10,000 | 18% |
| $10,001 – $20,000 | 20% |
| $20,001 – $40,000 | 22% |
| $40,001 – $60,000 | 24% |
| $60,001 – $80,000 | 26% |
| $80,001 – $100,000 | 28% |
| $100,001 – $150,000 | 30% |
| $150,001 – $250,000 | 32% |
| $250,001 – $500,000 | 34% |
| $500,001 – $750,000 | 37% |
| $750,001 – $1,000,000 | 39% |
| Over $1,000,000 | 40% |
Gifts that are never taxed
These don’t count toward your annual exclusion or lifetime exemption, at any amount:
- Tuition paid directly to a school. Tuition only, not books, housing, or fees, and the payment has to go to the school, not to the student.
- Medical bills paid directly to a provider, including health insurance premiums. Paying someone back for a bill doesn’t count.
- Gifts to a spouse who’s a U.S. citizen. If your spouse isn’t a citizen, the first $194,000 a year is tax-free in 2026 ($190,000 in 2025).
- Donations to qualified charities. No gift tax applies, but if you’re filing Form 709 anyway, list them on it. Here’s how charitable donations can also lower your income tax.
- Gifts to political organizations.
529 college savings plans get a special rule. You can put up to $95,000 into one child’s 529 in 2026, or $190,000 as a couple, and elect on Form 709 to spread it over five years of annual exclusions. That uses no lifetime exemption, but it uses up your annual exclusion for that child for all five years.
Form 709: when you have to file
File Form 709, the federal gift tax return, for 2026 if any of these apply:
- You gave someone other than your spouse more than $19,000 during the year.
- You and your spouse are electing to split gifts, at any amount.
- You gave a gift of a future interest, like most gifts to a trust, at any amount.
- You’re making the five-year election for a 529 plan contribution.
Form 709 for 2026 gifts is due April 15, 2027. If you extend your income tax return, the gift tax return is extended to October 15 too, or you can extend it alone with Form 8892. An extension doesn’t extend the time to pay any gift tax you owe. There’s no joint gift tax return. Each spouse who has to file files their own.
If no tax is due, a late or missing Form 709 usually doesn’t bring a penalty, because the late-filing penalty is a percentage of tax owed. The bigger risk is that the IRS’s three-year window to question a gift’s value doesn’t start until you report it, so a missed return leaves the gift open forever. For stock in a private company, real estate, or other hard-to-value gifts, get a qualified appraisal and attach it to the return.
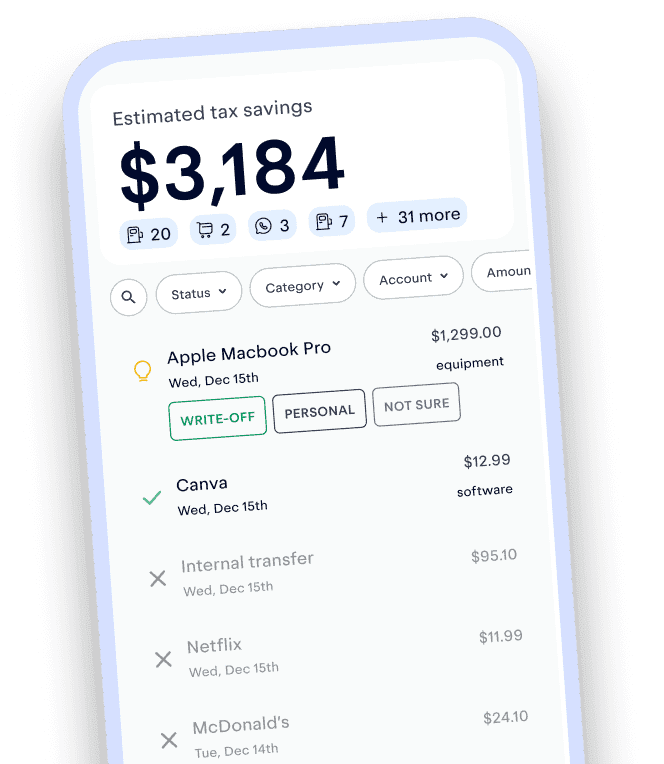
Track and claim every eligible deduction with Keeper
Keeper scans your accounts for write-offs and files your return — with tax pros reviewing every one.
Try it freeState gift taxes
Connecticut is the only state with its own gift tax. It uses the same $15 million lifetime exemption as the federal rules in 2026 and taxes gifts above it at 12%, so most Connecticut residents won’t owe it either. A few states with estate taxes add back gifts made shortly before death when they figure the estate tax.
Gift tax vs. estate tax vs. inheritance tax
- Gift tax is on what you give away while you’re alive. The giver pays.
- Estate tax is on what you leave when you die. It shares the gift tax’s $15 million exemption and 40% top rate, and your estate pays.
- Inheritance tax is a state tax some heirs pay on what they inherit. There’s no federal inheritance tax, and only a handful of states have one.
Thinking about gifts to clients or employees instead? Those are a business write-off question, not a gift tax one. See whether business gifts are deductible.
8 sources
- Rev. Proc. 2025-32: 2026 inflation adjustments (annual exclusion, basic exclusion amount) · irs.gov
- Rev. Proc. 2024-40: 2025 inflation adjustments · irs.gov
- Instructions for Form 709 · irs.gov
- Frequently asked questions on gift taxes · irs.gov
- Publication 551, Basis of Assets · irs.gov
- Gifts from foreign person · irs.gov
- 26 U.S. Code § 2001: Imposition and rate of tax · law.cornell.edu
- Connecticut DRS: Estate and gift tax information · portal.ct.gov
This article is for informational purposes only and isn’t tax, legal, or financial advice. Tax rules change and depend on your situation, so talk to a tax professional about yours.