How self-employment tax works in 2026

 Sarah York, EASarah is an Enrolled Agent with the IRS and a former staff writer at Keeper. In 2022, she was named one of CPA Practice Advisor’s 20 Under 40 Top Influencers in the field of accounting. Her work has been featured in Business Insider, Money Under 30, Best Life, GOBankingRates, and Shopify. Sarah has spent nearly a decade in public accounting and has extensive experience offering strategic tax planning at the state and federal levels. Her clients have come from a wide range of industries, including oil and gas, manufacturing, real estate, wholesale and retail, finance, and ecommerce, and she has handled tax returns for C corps, S corps, partnerships, nonprofits, and sole proprietorships. In her spare time, she is a devoted cat mom and enjoys hiking, painting, and overwatering her houseplants.
 Krislyn ChanKrislyn is Chief Growth Officer at Keeper. At Keeper, she strives to make expert-level tax strategies that used to require a traditional CPA accessible to all. Prior to Keeper, she was at Curology, where she helped bring custom, prescription-grade skincare out of the dermatologist's office to millions of faces.

Key takeaways
- Set aside 25–30% of your profit in a high-yield savings account. That covers self-employment tax, federal income tax, and state tax for most freelancers.
- Self-employment tax is about 14.1% of your profit. It’s 15.3% (12.4% Social Security plus 2.9% Medicare) on 92.35% of your profit.
- The 12.4% Social Security tax only applies to your first $184,500 of earnings in 2026. Earnings above that aren’t charged Social Security tax, and your W-2 wages count toward the $184,500. Medicare has no limit, and higher earners pay an extra 0.9%.
- You deduct half of your self-employment tax when figuring your income tax, so it costs a bit less than it looks.
- Pay quarterly estimated taxes if you expect to owe $1,000 or more for the year. Get your amounts with the quarterly tax calculator.
How much should you set aside for taxes?
Here’s how much federal tax a single freelancer with no other income would owe in 2026, and what share of their profit that is. These figures assume the standard deduction and no kids or tax credits.
| 1099 profit | Self-employment tax | Federal income tax | Total federal tax | % of profit |
|---|---|---|---|---|
| $20,000 | $2,826 | $199 | $3,025 | 15.1% |
| $40,000 | $5,652 | $1,775 | $7,427 | 18.6% |
| $60,000 | $8,478 | $3,559 | $12,037 | 20.1% |
| $80,000 | $11,304 | $5,344 | $16,647 | 20.8% |
| $100,000 | $14,130 | $8,235 | $22,365 | 22.4% |
| $150,000 | $21,194 | $16,413 | $37,608 | 25.1% |
Add your state’s income tax on top, which is why 25–30% is the safer target. For your full bill, including state tax, use the 1099 tax calculator or find your state’s 1099 tax calculator.
How self-employment tax is calculated
Self-employment tax is how you pay Social Security and Medicare when you work for yourself. Employees split it with their employer, 7.65% each. You pay both halves, 15.3%, but the IRS adjusts for that in two ways. Here’s the math at $80,000 of profit:
| Step | Amount |
|---|---|
| Profit (1099 income minus business expenses) | $80,000 |
| Net earnings from self-employment: $80,000 × 92.35% | $73,880 |
| Social Security: 12.4% (up to $184,500 of earnings) | $9,161 |
| Medicare: 2.9% (no limit) | $2,143 |
| Self-employment tax | $11,304 |
| Half you deduct when figuring income tax | $5,652 |
- Why 92.35%: an employer doesn’t pay Social Security and Medicare tax on its own half of those taxes, so the IRS takes 7.65% off your profit before applying the rate.
- Why you deduct half: an employee never pays income tax on the half their employer covers, so you subtract half of your self-employment tax from your income.
- When you owe it: once your net earnings from self-employment are $400 or more for the year, whether or not you got a 1099.
- Higher earners: an extra 0.9% Medicare tax applies to earnings above $200,000 ($250,000 married filing jointly), counting wages and self-employment earnings together. You can’t deduct half of that part.
If you also have a W-2 job
Your W-2 wages count toward the $184,500 Social Security limit first. Say you earn $150,000 at your job and make $50,000 from a side business. Only $34,500 of room is left under the limit, so you pay the 12.4% Social Security part on that much and the 2.9% Medicare part on all of it. Your self-employment tax is about $5,617 instead of $7,065.
Do self-employed people pay more in taxes?
On Social Security and Medicare, yes: you pay the employer’s half too, which adds about 7% of your profit. Deducting half of your self-employment tax gives a little of that back in lower income tax. You also get breaks employees don’t:
- Business write-offs lower both your self-employment tax and your income tax.
- The QBI deduction lets most freelancers deduct 20% of their business profit from their income tax.
Self-employment taxes also feel bigger because nothing is withheld from your pay. Employees pay all year through their paychecks. You pay through estimated taxes, or all at once when you file.
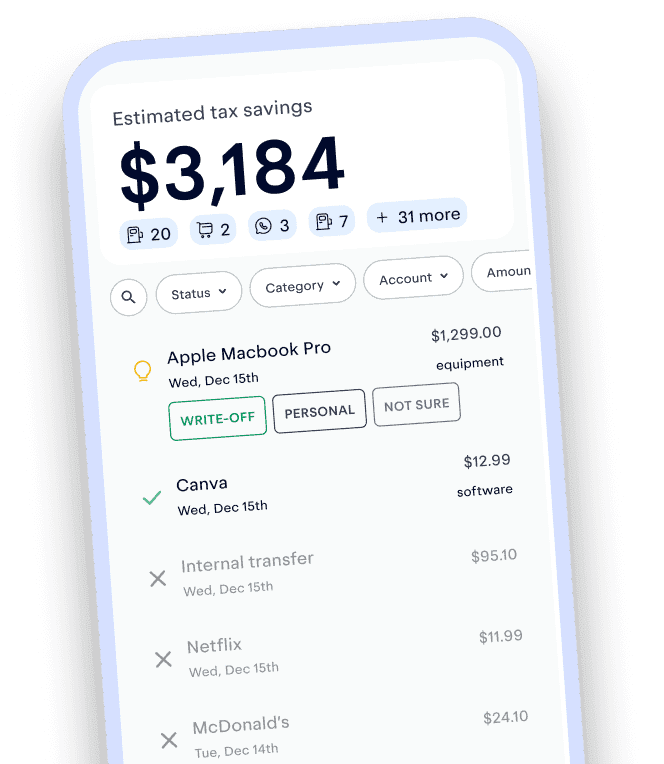
Track and claim every eligible deduction with Keeper
Keeper scans your accounts for write-offs and files your return — with tax pros reviewing every one.
Try it freeHow to budget for self-employment taxes
The US has a pay-as-you-go tax system, which means taxes are due as you earn your income, not when you file your return. If you expect to owe $1,000 or more for the year, make quarterly estimated tax payments to avoid penalties and interest. These habits make it easier:
- Save 25–30% of every payment for taxes. Each time a client pays you, move that share into a separate high-yield savings account, so it earns interest until your payments are due.
- Automate it. Most banks can move money between accounts on a schedule, so you save without thinking about it.
- Pay more often than quarterly if it helps. The IRS accepts payments any time. Some freelancers pay monthly so the money never piles up.
- Put it somewhere you won’t touch. An account at a different bank, with no debit card and no payment apps connected, keeps tax money from turning into spending money.
- Price your work with taxes in mind. If you’re used to a W-2 salary, raise your rate to cover the self-employment tax an employer used to pay. See our freelancer invoice template.
How to lower your self-employment tax
Self-employment tax is figured on your profit, so every business expense you deduct lowers it, along with your income tax. Common ones include your phone, car expenses, a home office, and software. See the full list of tax write-offs for self-employed people.
Once your profit is high enough, an S corp election can cut self-employment tax further. You pay yourself a reasonable salary and take the rest as profit payouts that aren’t subject to it. Run the numbers for your income.
6 sources
- Topic no. 554, Self-employment tax · irs.gov
- Self-employment tax (Social Security and Medicare taxes) · irs.gov
- Contribution and benefit base · ssa.gov
- Questions and answers for the Additional Medicare Tax · irs.gov
- Estimated taxes · irs.gov
- IRS releases tax inflation adjustments for tax year 2026 · irs.gov
This article is for informational purposes only and isn’t tax, legal, or financial advice. Tax rules change and depend on your situation, so talk to a tax professional about yours.