Income taxes in 2026: how your refund is calculated

 Sarah York, EASarah is an Enrolled Agent with the IRS and a former staff writer at Keeper. In 2022, she was named one of CPA Practice Advisor’s 20 Under 40 Top Influencers in the field of accounting. Her work has been featured in Business Insider, Money Under 30, Best Life, GOBankingRates, and Shopify. Sarah has spent nearly a decade in public accounting and has extensive experience offering strategic tax planning at the state and federal levels. Her clients have come from a wide range of industries, including oil and gas, manufacturing, real estate, wholesale and retail, finance, and ecommerce, and she has handled tax returns for C corps, S corps, partnerships, nonprofits, and sole proprietorships. In her spare time, she is a devoted cat mom and enjoys hiking, painting, and overwatering her houseplants.
 Krislyn ChanKrislyn Chan is a consumer subscription growth leader who has spent her career making premium services affordable and accessible. As Chief Growth Officer at Keeper, she drives growth for a platform that pairs AI with licensed tax professionals to help self-employed people keep more of what they earn. She has written more than 50 Keeper guides on tax strategy for freelancers, independent contractors, and small business owners. Previously, Krislyn was at Curology, where she helped turn dermatologist-grade custom skincare into a direct-to-consumer subscription used by millions.

Key takeaways
- How your refund is calculated: add up the tax withheld from your paychecks, your estimated payments, and any refundable credits, then subtract your total tax. If you paid more than you owe, you get the difference back. If you paid less, you owe the rest.
- 2026 standard deduction: $16,100 for single filers, $32,200 for married couples filing jointly, and $24,150 for heads of household. Income above that is taxed in brackets from 10% to 37%.
- New deductions for 2026: you can deduct up to $25,000 of tip income, up to $12,500 of overtime premium pay ($25,000 if married filing jointly), $6,000 for each person 65 or older, and up to $1,000 of cash donations ($2,000 jointly) even if you don’t itemize.
- You owe 15.3% self-employment tax on 1099 income: unlike W-2 wages, where your employer withholds tax from each paycheck and pays half of your Social Security and Medicare, nothing is withheld from 1099 income. You pay both halves yourself, on 92.35% of your profit, on top of income tax. That’s the most common reason why self-employed workers owe at tax time.
- Writing off your business expenses is the biggest lever you can use to lower self-employment taxes. Every dollar of business expenses lowers both your income tax and your self-employment tax. Find your write-offs with Keeper.
How this income tax calculator works
Enter your expected amounts for the full 2026 tax year. The calculator calculates your federal income tax, self-employment tax, and state income tax, subtracts what you’ve paid, and shows your refund or balance due.
| Input | What to include |
|---|---|
| Filing status and dependents | The status you’ll file under. Dependents count toward the child tax credit and the earned income credit. |
| Age 65 or older | Check if you (or your spouse, if filing jointly) will be 65 or older by December 31. |
| Employment income (W-2) | Your wages for the year, including any tips and overtime your employer paid you. |
| Freelance / business / 1099 income | Everything your business or side gig brought in, whether or not you got a 1099 for it. |
| Business expenses | Ordinary and necessary costs of that work, like supplies, software, and business mileage. |
| Tips and overtime premium pay | Tips you received, and the extra “half” of time-and-a-half overtime. Keep them in your income too; these fields only size the deductions. |
| Charitable donations, mortgage interest, tuition, IRA contributions | Optional. They can lower your tax through deductions and the American Opportunity credit. |
| Taxes withheld and quarterly payments | Optional. Leave withholding blank and the calculator estimates it from your W-2 wages. Add any estimated payments you’ve made. |
What the estimate includes
The calculator uses 2026 brackets and standard deductions, self-employment tax, the qualified business income (QBI) deduction, the child tax credit, the earned income credit, the American Opportunity credit, and state income tax. Tips, overtime, and senior deductions are applied to your federal tax only, since many states don’t follow them.
It doesn’t include investment income, rental income, retirement withdrawals, Social Security benefits, the alternative minimum tax, or local income taxes. Treat the result as an estimate.
Example: a W-2 job and a side business
Say you’re single, earn $50,000 at a W-2 job, and make $30,000 profit freelancing on the side in 2026:
- Self-employment tax: $30,000 × 92.35% × 15.3% = $4,239
- Adjusted gross income: $80,000 minus half your self-employment tax ($2,119) = $77,881
- Taxable income: $77,881 minus the $16,100 standard deduction and a $5,576 QBI deduction = $56,205
- Federal income tax on $56,205, from the IRS tax table: $7,082
Your total federal tax is $11,321, about 14% of your $80,000. Your employer withholds only for your salary, so the freelance income adds roughly $7,500 to your bill with nothing withheld toward it.
Employed and self-employed? How W-2 and 1099 income are taxed together
If you have a job and a side business, both incomes are added together and taxed in the same brackets. Your 1099 income lands on top of your wages, so it’s often taxed at your highest rate. The difference is what gets withheld:
- W-2 wages: your employer withholds income tax and your share of Social Security and Medicare (7.65%) from each paycheck.
- 1099 income: nothing is withheld. You owe income tax plus 15.3% self-employment tax on 92.35% of your profit, and you can deduct half of the self-employment tax.
- Social Security cap: the 12.4% Social Security part only applies up to $184,500 of combined wages and self-employment earnings in 2026. Your W-2 wages count first.
To avoid a surprise bill, cover the tax on your 1099 income during the year in one of two ways:
- Raise your paycheck withholding. Add an extra amount on line 4(c) of a new Form W-4. Withholding counts as paid evenly through the year, even if you increase it late.
- Make quarterly estimated payments. Use our quarterly tax calculator to size them.
Only have 1099 income? Our self-employment tax rate calculator shows what percentage of your income to set aside for taxes.
What taxes do you pay when you file your return?
Most people’s return comes down to two taxes: income tax on everything you earn, and self-employment tax if you have freelance, side hustle, or small-business income.
How the progressive tax system works
Your taxable income is split into layers, and each layer is taxed at its own rate. Only the income inside a bracket is taxed at that bracket’s rate, so moving into a higher bracket never lowers your take-home pay.
For example, a single filer with $76,100 in wages takes the $16,100 standard deduction, leaving $60,000 of taxable income. In 2026, that’s taxed like this:
| Bracket | Income in the bracket | Tax |
|---|---|---|
| 10% | $12,400 | $1,240 |
| 12% | $38,000 | $4,560 |
| 22% | $9,600 | $2,112 |
| Total | $60,000 | $7,912 |
Your marginal tax rate is the rate on your last dollar of taxable income: 22% here. Your effective tax rate is your total tax divided by your income: $7,912 ÷ $76,100 = about 10.4%.
To find your own marginal and effective tax rates, use our tax bracket calculator.
The 2026 income tax brackets, by filing status
Brackets depend on your filing status: single, married filing jointly, married filing separately, or head of household. These are the brackets for 2026 returns filed in 2027:
| Tax rate | Single | Married filing jointly | Married filing separately | Head of household |
|---|---|---|---|---|
| 10% | $0 to $12,400 | $0 to $24,800 | $0 to $12,400 | $0 to $17,700 |
| 12% | $12,401 to $50,400 | $24,801 to $100,800 | $12,401 to $50,400 | $17,701 to $67,450 |
| 22% | $50,401 to $105,700 | $100,801 to $211,400 | $50,401 to $105,700 | $67,451 to $105,700 |
| 24% | $105,701 to $201,775 | $211,401 to $403,550 | $105,701 to $201,775 | $105,701 to $201,750 |
| 32% | $201,776 to $256,225 | $403,551 to $512,450 | $201,776 to $256,225 | $201,751 to $256,200 |
| 35% | $256,226 to $640,600 | $512,451 to $768,700 | $256,226 to $384,350 | $256,201 to $640,600 |
| 37% | $640,601 and up | $768,701 and up | $384,351 and up | $640,601 and up |
Self-employment tax
Self-employment tax is Social Security and Medicare for people who work for themselves. W-2 employees split these taxes with their employer, and the employee half comes out of each paycheck. When you’re self-employed, you pay both halves: 12.4% for Social Security (on up to $184,500 in 2026) and 2.9% for Medicare, for 15.3% in total.
It applies to 92.35% of your net profit once that profit is $400 or more, and you can deduct half of it from your income. An extra 0.9% Medicare tax applies to earnings over $200,000 ($250,000 if married filing jointly). Learn more in our guide to self-employment taxes.
What’s new for 2026 taxes
The 2025 tax law, known as the One Big Beautiful Bill Act, changed several deductions and credits. Here’s what applies to 2026 returns:
- Higher standard deduction: $16,100 single, $32,200 married filing jointly, $24,150 head of household.
- No tax on tips: deduct up to $25,000 of qualified tips from jobs where tipping is customary, through 2028. It shrinks once income passes $150,000 ($300,000 jointly).
- No tax on overtime: deduct the premium part of required overtime pay, up to $12,500 ($25,000 jointly), through 2028, with the same income limits as tips.
- Senior deduction: an extra $6,000 for each person 65 or older, through 2028. It shrinks by 6% of income over $75,000 ($150,000 jointly).
- Charitable giving without itemizing: new in 2026, deduct up to $1,000 ($2,000 jointly) of cash donations even if you take the standard deduction.
- Car loan interest: deduct up to $10,000 of interest on a loan for a new, US-assembled personal vehicle taken out after 2024. The calculator doesn’t include this one.
- State and local tax (SALT) cap: $40,400 for 2026 if you itemize, reduced for income over $505,000.
- Child tax credit: $2,200 per child under 17, with up to $1,700 refundable.
- 1099 thresholds: clients send a 1099-NEC once they pay you $2,000 or more, and payment apps send a 1099-K once you pass $20,000 and 200 transactions. You owe tax on all your income either way.
Married couples filing separately can’t take the tips, overtime, or senior deductions. All three come off your taxable income whether or not you itemize.
How do you lower your tax bill?
Step 1: Claim your business write-offs
If you have freelance income or a side hustle, business write-offs are the only way to directly lower your self-employment tax. A write-off is any work-related cost that’s ordinary in your industry and necessary for doing the job.
What tax write-offs can I claim?
People often skip write-offs because they picture things like computers, software, and office supplies. But what counts depends on your work. A pet groomer needs shears, shampoo, and treats. A freelance photographer needs ring lights, props, and lenses. Our freelance tax deductions tool lists common write-offs by job.
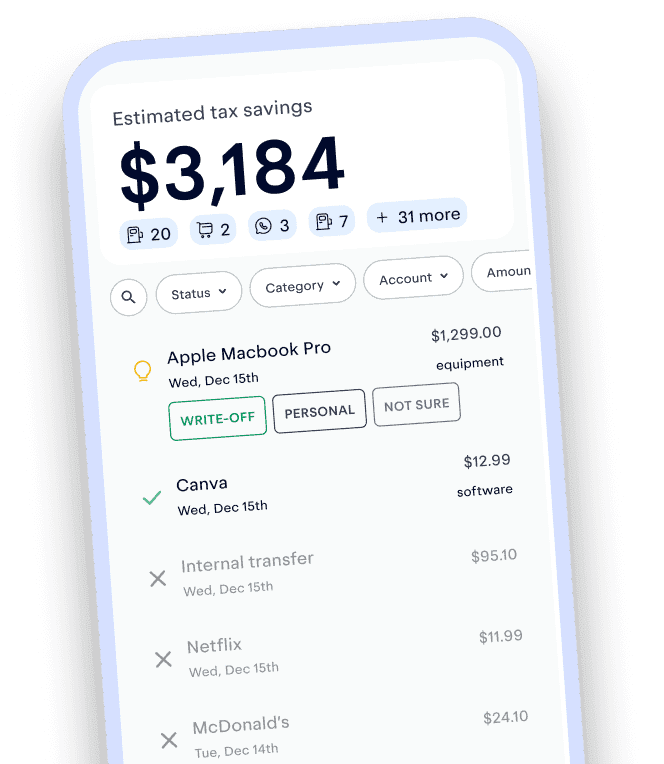
Track and claim every eligible deduction with Keeper
Keeper scans your accounts for write-offs and files your return — with tax pros reviewing every one.
Try it freeStep 2: Take your income adjustments
Adjustments come off your income before your deductions, so they lower your adjusted gross income. Common ones include:
- Educator expenses (up to $350 for K–12 teachers)
- Traditional IRA contributions (up to $7,500, or $8,600 if you’re 50 or older)
- SEP-IRA and solo 401(k) contributions if you’re self-employed
- HSA contributions
- Self-employed health insurance
- Student loan interest (up to $2,500)
- Alimony you pay under a divorce or separation agreement signed before 2019
- Half of your self-employment tax
Step 3: Take the bigger of the standard or itemized deduction
You can take the standard deduction or itemize deductions like mortgage interest, state and local taxes, and charitable gifts, whichever is larger. Either way, it’s on top of your business write-offs.
| Filing status | Standard deduction (2026) |
|---|---|
| Single or married filing separately | $16,100 |
| Married filing jointly | $32,200 |
| Head of household | $24,150 |
If you’re 65 or older or blind, your standard deduction is higher: $2,050 more if you’re unmarried, or $1,650 more per qualifying spouse if you’re married. The $6,000 senior deduction comes on top of that.
Step 4: Claim your tax credits
Credits lower your tax dollar for dollar. Refundable credits can be paid to you as a refund even if you owe no tax. Nonrefundable credits can lower your tax to zero, but not below.
Common refundable credits:
- 💰 Earned income credit: for workers with low to moderate income. In 2026 it’s worth up to $664 with no children and up to $8,231 with three or more, depending on income limits.
- 🍼 Child tax credit: up to $2,200 per child under 17. It’s partly refundable: up to $1,700 per child can come back as a refund.
- 🎒 American Opportunity credit: up to $2,500 a year for each student in their first four years of college. Up to $1,000 of it is refundable.
- 🏥 Premium tax credit: helps pay for health insurance bought through the Marketplace, usually paid in advance during the year.
- 👪 Adoption credit: up to $17,670 per child in 2026, and up to $5,120 of it is now refundable.
Common nonrefundable credits:
- 🏦 Saver’s credit: for retirement contributions if your income is under certain limits. Up to $1,000 ($2,000 if married filing jointly).
- 📚 Lifetime Learning credit: 20% of up to $10,000 in education costs, for a maximum of $2,000 per return.
- 👶 Child and dependent care credit: 20% to 50% of up to $3,000 in care costs for one child under 13 or other dependent ($6,000 for two or more). The 50% rate is new for 2026 and applies at lower incomes.
- 👧 Credit for other dependents: $500 for each dependent who doesn’t qualify for the child tax credit.
- 🌍 Foreign tax credit: for income tax you paid to another country.
How to stay on top of your tax bill
No one withholds tax from self-employment income, so the IRS expects you to pay as you go with estimated tax payments during the year.
Making estimated tax payments
The four payment periods aren’t equal calendar quarters. For the 2026 tax year, payments are due:
| Income earned | Due date |
|---|---|
| January 1 to March 31, 2026 | April 15, 2026 |
| April 1 to May 31, 2026 | June 15, 2026 |
| June 1 to August 31, 2026 | September 15, 2026 |
| September 1 to December 31, 2026 | January 15, 2027 |
Use our quarterly tax calculator to figure out each payment, or schedule your federal payments with Keeper so they’re paid automatically on each due date.
Who should make estimated payments
You generally need to make estimated payments if you expect to owe $1,000 or more after withholding and credits. If you don’t pay enough on time, you may owe an underpayment penalty. It works like interest: the IRS charges the federal short-term rate plus 3 percentage points (7% a year for October through December 2026) on each underpaid amount until it’s paid.
You generally avoid the penalty if your withholding and on-time estimated payments cover either:
- 90% of your 2026 tax, or
- 100% of your 2025 tax (110% if your 2025 adjusted gross income was over $150,000, or $75,000 if married filing separately)
See what you’d owe with our estimated tax penalty calculator.
14 sources
- Rev. Proc. 2025-32: 2026 inflation adjustments (brackets, standard deduction, credits) · irs.gov
- Publication 505: tax withholding and estimated tax (2026) · irs.gov
- Working Families Tax Cuts: individuals and workers · irs.gov
- Schedule 1-A additional deductions: what to know about the new form · irs.gov
- Questions and answers about the new deduction for qualified overtime compensation · irs.gov
- One Big Beautiful Bill provisions · irs.gov
- Topic no. 554, Self-employment tax · irs.gov
- Child tax credit · irs.gov
- Education credits: AOTC and LLC · irs.gov
- Child and dependent care credit information · irs.gov
- Topic no. 452, Alimony and separate maintenance · irs.gov
- Interest rates remain the same for the fourth quarter of 2026 · irs.gov
- Repeal of the NH Interest and Dividends Tax now in effect · revenue.nh.gov
- Washington Department of Revenue: income tax · dor.wa.gov
This article is for informational purposes only and isn’t tax, legal, or financial advice. Tax rules change and depend on your situation, so talk to a tax professional about yours.




 By Soo Lee, CPA