

Key takeaways
The Qualified Business Income (QBI) deduction allows eligible business owners and self-employed individuals to deduct up to 20% of their qualified business income, reducing their taxable income.
This deduction, introduced by the Tax Cuts and Jobs Act (TCJA) in 2018 and made permanent by the One Big Beautiful Bill Act in 2025, applies to pass-through entities like sole proprietorships, partnerships, S corporations, and certain trusts and estates.
However, there are income thresholds and specific rules that may limit the deduction, especially for high-income earners and those in specified service trades or businesses (SSTBs). To claim the deduction, taxpayers must fill out Form 8995 or 8995-A, depending on their income level.
Starting in 2026, business owners with at least $1,000 of qualified business income from a business they actively run get a minimum deduction of $400.
The qualified business income (QBI) deduction is a tax break offering up to a 20% deduction to certain business owners and self-employed workers. It’s clearly a pretty big deal for anyone who has to handle self-employment taxes.
What is the qualified business income deduction?
The qualified business income (QBI) deduction is a tax break that lets business owners with pass-through income write off up to 20% of their qualified business income.
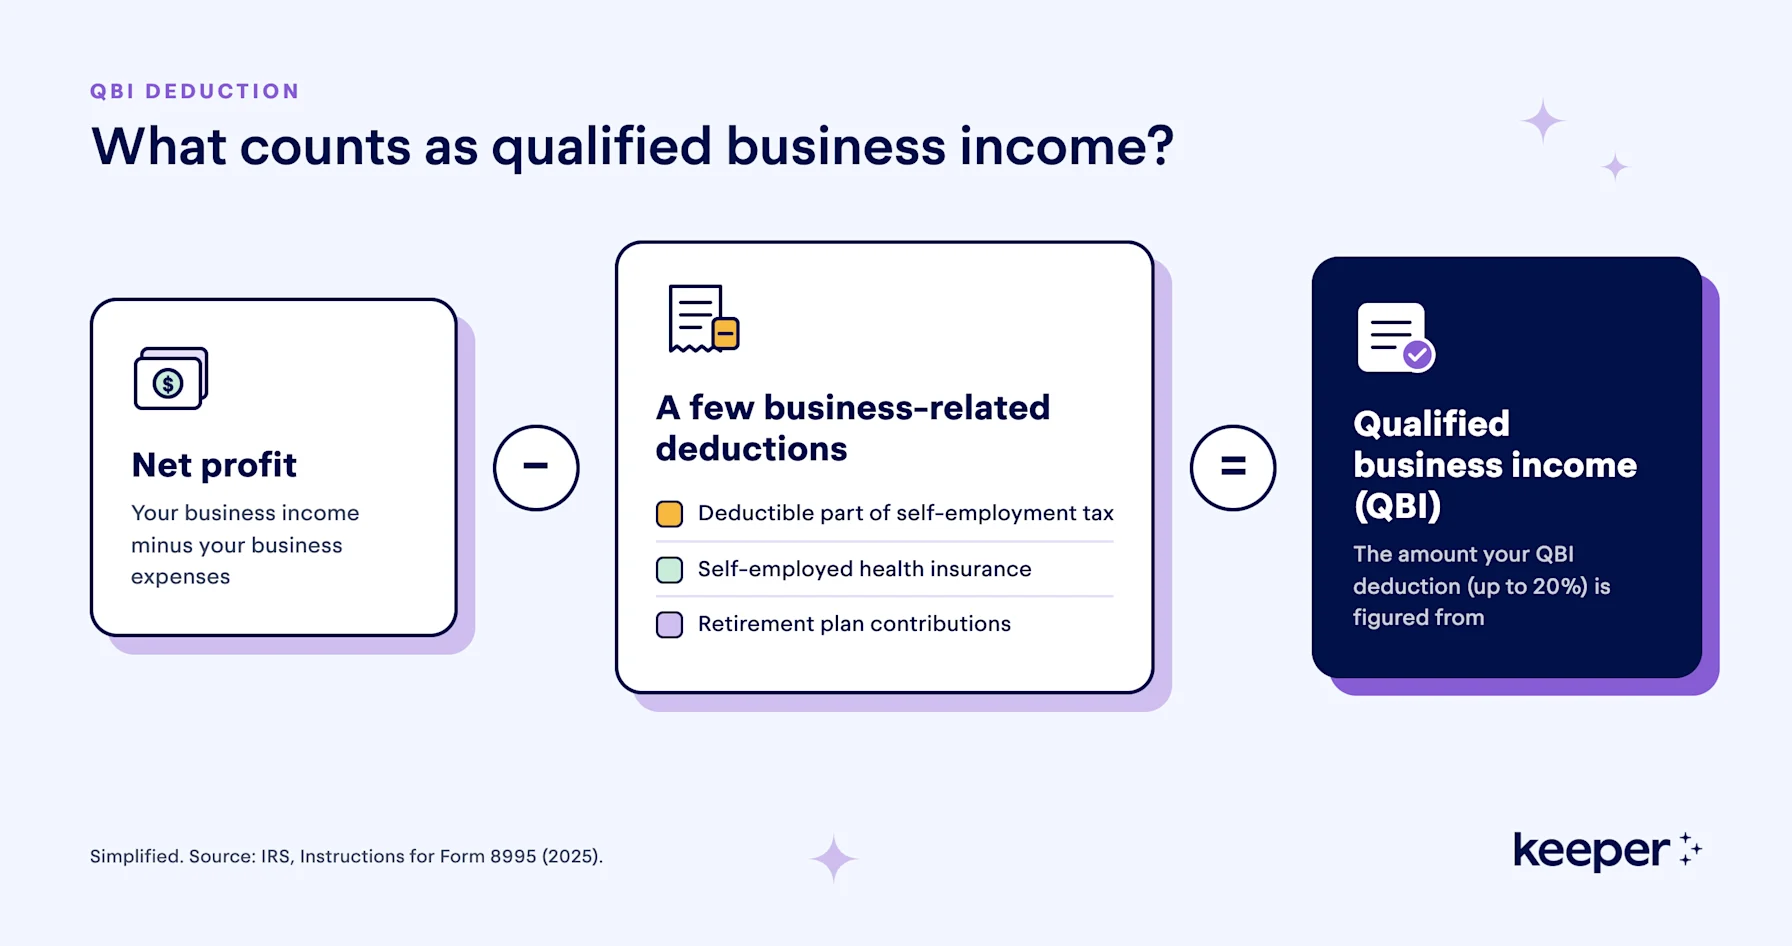
Your "qualified business income" is roughly your business's net profit, minus a few business-related deductions like the deductible part of self-employment tax, self-employed health insurance, and retirement plan contributions.
Also known as Section 199A, the QBI deduction was added to the US Tax Code by the Tax Cuts and Jobs Act (TCJA). It’s been available to eligible freelancers, independent contractors, and business owners since January 1, 2018. It was originally set to expire after 2025, but the One Big Beautiful Bill Act, signed in July 2025, made it permanent.
The history behind the QBI deduction
Workers with pass-through income have always had a unique tax advantage: Their business income is taxed once at the owner’s individual tax rates, instead of being taxed at the much higher corporate tax rate (35% before 2018) and then being taxed again when profits are paid out as dividends. Since most taxpayers’ rates fall between 12 and 22%, this created a huge competitive edge.
However, that advantage went away after the TCJA lowered the corporate tax rate to 21%. People were understandably upset. Imagine carefully choosing your business’s entity structure based on the potential tax savings… all for Congress to take it away with one fell swoop.
The QBI deduction was Congress's solution. They figured a 20% deduction would be enough to quell people’s outrage.
How does the QBI deduction work?
There are three important things to note about the QBI deduction:
✓ It doesn’t matter if you take the standard deduction or itemize
Both options qualify you for the QBI deduction.
✓ It doesn’t lower your self-employment tax
The QBI deduction only lowers your income taxes, not your self-employment taxes.
To lower your self-employment taxes, take advantage of business write-offs! Ordinary and necessary business expenses reduce your net earnings, which lowers both self-employment tax and income tax.
Not sure what counts? You can use Keeper to scan your purchases and automatically deduct everything that’s an eligible business write-off in your industry.
What tax write-offs can I claim?
✓ It can impact retirement planning
You can’t apply the 20% QBI write-off to money that’s been put into a tax-deductible retirement plan, like a 401(k) or SEP-IRA.
Let’s take a step back to dig into the implications here.
When self-employed people put money into their 401(k)s, the amount they contribute can be deducted from their business income.
But because taking that deduction lowers their business income, it also lowers the amount of their QBI write-off. After all, 20% of $40,000 is less than 20% of $50,000.
Because of this, business owners are faced with a decision between short-term and long-term savings. If you forego your retirement savings in favor of more QBI, you’ll reduce the amount of tax you owe the IRS right now. But the trade off is, you’ll miss out on the long-term benefits of 401(k) contributions.
Who’s eligible for the QBI deduction?
Let’s zero in on the kinds of freelancers and business owners that are eligible for the deduction.
Business owners with pass-through income
A pass-through business is one that’s not subject to corporate income tax. Instead, all its income “passes through” to the owner, who reports it on their personal tax return.
People who have pass-through income include:
Sole proprietors: A single individual, often a freelancer or independent contractor, who owns an unincorporated business
Partnership members: Two or more people who made a formal agreement to run a business together, such as a law firm
S corporation shareholders: People who own interest in an S corp and report the company’s corporate income, losses, deductions, and credits on their personal tax returns
Limited Liability Company (LLC) members: Owners of an LLC that’s taxed as either a sole proprietorship, a partnership, or an S corp
Beneficial owners of a trust or estate: Not all trusts or estates qualify, and the rules get complicated fast - talk to a Keeper tax pro if this is you!
After seeing such a laundry list, you might be wondering, “What business owners don’t qualify?”
The answer: People with C corporations. Unlike pass-through businesses, C corps do pay corporate income taxes and therefore can’t claim the QBI deduction.
Track and claim every eligible deduction with Keeper
Keeper scans your accounts for write-offs and files your return — with tax pros reviewing every one.
Try it freePeople with qualified REIT dividends or PTP income
Business owners aren’t the only people who can benefit from the QBI deduction. Those with qualified dividends from a real estate investment trust (REIT) or income from a publicly traded partnership (PTP) can also claim a 20% QBI deduction.
If you have both types of income, these QBI benefits actually stack. For example, if you have a sole proprietorship for your freelance work and also receive qualified dividends from an REIT, you can deduct 20% from your freelance income and 20% from your REIT dividends.
To count, you generally need to have held the REIT shares for more than 45 days. They don’t include capital gains or regular qualified dividends.
What doesn’t count as qualified business income?
For deduction purposes, these types of income are excluded from QBI:
Earnings from a W-2 job (if you have a side hustle)
Income from business outside of the United States
Interest income unrelated to a trade or business
Annuities received from something other than a trade or business
Guaranteed payments from a partnership
Reasonable compensation (salary) an S corporation pays you
Investment items like capital gains, capital losses, or dividends
For a full list of what the IRS doesn’t consider qualified business income, head here.
How is the QBI deduction calculated?
Typically, your QBI deduction is the smaller amount between these two options:
20% of your QBI, plus 20% of your REIT dividends and PTP income
20% of your taxable income, minus net capital gains
Starting in 2026, if you have at least $1,000 of qualified business income from a business you materially participate in, your deduction is at least $400.
If you’re a typical freelancer, independent contractor, or small business owner, that’s really all you need to know. Feel free to skip to the section on claiming your QBI deduction!
On the other hand, maybe you have a more complicated situation — like earning high self-employment income or working in certain industries like law or medicine. In that case, there will be limits placed on the amount of QBI you can claim.
There are also special circumstances with people who own multiple businesses.
Limitations on QBI deductions
If your taxable income is above a certain threshold — or generated by certain trades — you may only be able to claim a portion of the deduction. At certain levels, you stop being eligible for the deduction altogether.
Let’s go over when these limitations apply to the amount you can deduct.
If your taxable income is above the IRS’s thresholds
When it comes to the QBI deduction, there are actually two income thresholds you have to deal with.
The lower QBI threshold
The lower threshold is what you need to stay at or below to get the full 20% deduction. If your taxable income is above this amount, then your QBI deduction starts to get reduced. This income limit changes every year based on inflation.
2025 | 2026 | |
|---|---|---|
Lower threshold, single filers | $197,300 | $201,750 |
Lower threshold, joint filers | $394,600 | $403,500 |
The higher QBI threshold
At the second, higher income threshold, things start to change again. (Thanks, IRS!)
2025 | 2026 | |
|---|---|---|
Upper threshold, single filers | $247,300 | $276,750 |
Upper threshold, joint filers | $494,600 | $553,500 |
Notice the bigger jump for 2026. The One Big Beautiful Bill Act widened the gap between the two thresholds from $50,000 to $75,000 for single filers (and from $100,000 to $150,000 for joint filers), so more people keep at least part of the deduction.
For most businesses, these thresholds work like a dimmer switch, not an on/off switch:
At or below the lower threshold: You get the full 20% deduction, no matter how much (or how little) your business pays in wages.
Between the two thresholds: A wage-and-property cap starts to phase in. The further your income climbs through this range, the more of the cap applies.
Above the upper threshold: The cap applies in full. Your deduction can't be more than the greater of:
50% of the W-2 wages paid by your business, or
25% of the W-2 wages, plus 2.5% of qualified depreciable property (like buildings and equipment)
This matters a lot for solo freelancers. If your business pays no W-2 wages and owns no significant property, the cap is $0. That means your deduction starts shrinking as soon as your taxable income passes the lower threshold, and (apart from the $400 minimum starting in 2026) it's gone once you pass the upper one.
There are exceptions based on your industry, though. (More on those below!)
Finding your QBI deduction after the higher threshold
To give an example, let’s say you're a single filer and have $300,000 of taxable income, $100,000 of which is from your business. You also paid $30,000 of wages and you own an office building that originally cost $480,000 (its "unadjusted basis").
Normally, you would be able to claim a $20,000 QBI deduction on your business income of $100,000 ($100,000 x 0.20 = $20,000).
But because your taxable income exceeds the limit for single filers, you have to use the calculations above to figure out your QBI deduction. Here’s how that would look:
Option A: $30,000 x 0.50 = $15,000
Option B: ($30,000 x 0.25) + ($480,000 x 0.025) = $19,500
In this scenario, option B results in the higher deduction. Since that's less than the normal $20,000, your QBI deduction is $19,500.
If you own a “specified service trade or business”
A specified service trade or business (SSTB) is a business in one of the fields the tax code singles out - mostly professional and financial services where you're selling expertise rather than products. (The rules also sweep in anyone whose business is built on personal fame: endorsement deals, licensing your name or likeness, and paid appearances.)
What counts as an SSTB?
SSTBs include service businesses in:
Healthcare
Law
Accounting
Athletics
Consulting
Performing arts
…and more. Check out the full list here.
How QBI limits work for SSTBs
The QBI deduction an SSTB can claim is also based on their income level and filing status. What makes the SSTB designation unfortunate, is that — unlike everybody else — you can’t claim any deduction after you hit the income ceiling.
Here are the figures for the 2025 and 2026 tax years:
Filing status | 2025 | 2026 | Eligible QBI deduction |
|---|---|---|---|
Single tax filer | Up to $197,300 | Up to $201,750 | 20% |
Single tax filer | $197,300 – $247,300 | $201,750 – $276,750 | Partial deduction |
Single tax filer | Over $247,300 | Over $276,750 | 0% |
Married filing jointly | Up to $394,600 | Up to $403,500 | 20% |
Married filing jointly | $394,600 – $494,600 | $403,500 – $553,500 | Partial deduction |
Married filing jointly | Over $494,600 | Over $553,500 | 0% |
If you recently bought partnership interest
Luckily, most small business owners don’t have to deal with this limit, because it’s a little complicated. It’s calculated as a percentage of their wages, plus a different percentage of the “unadjusted basis immediately after acquisition” (UBIA). “Unadjusted basis” just means how much it originally cost to purchase the partnership’s property.
In a nutshell, people in this situation have their QBI deduction capped at the sum of:
25% of the W-2 wages paid
2.5% of its UBIA
The business figures its W-2 wages and UBIA and passes your share through to you on your Schedule K-1, so you don't have to calculate them yourself.
For people with multiple businesses
If you own multiple pass-through businesses, you can opt to aggregate your business interests, which, in some circumstances, may give you a larger QBI deduction.
There are some limitations to who’s allowed to aggregate their businesses. For instance, your businesses can’t be SSTBs and need to be connected in some meaningful way. You can learn more here!
Now that we’re all clear on who can claim the QBI deduction — or portions of it — let’s move on to how you go about it.
How to claim the QBI deduction
This is a dense subject, and there’s a lot to cover. It’s the rare case where you can’t see the trees for the forest, because the overall concept is so hard to grasp.
The solution? Let’s break down the steps of applying for the QBI deduction, which aren’t all that complicated.
Step #1: Determine your taxable income
Your taxable income is your total income minus any deductions you're entitled to claim, including your business write-offs and the standard deduction.
Even before your QBI deduction kicks in, you can lower your taxable income off the bat by keeping thorough expense records throughout the year. That way, you’ll know what you can write off.
If you haven’t been quite on top of your bookkeeping, don’t worry! The Keeper app offers a built-in deduction tracker that scans your purchases and finds qualifying business expenses for you. After everything's accounted for, you can file with Keeper too.
Over 1M Americans trust Keeper for their complex taxes
The #1 tax app for freelancers, gig workers, and self-employed filers.
Get started free
Step #2: Fill out Form 8995 or 8995-A
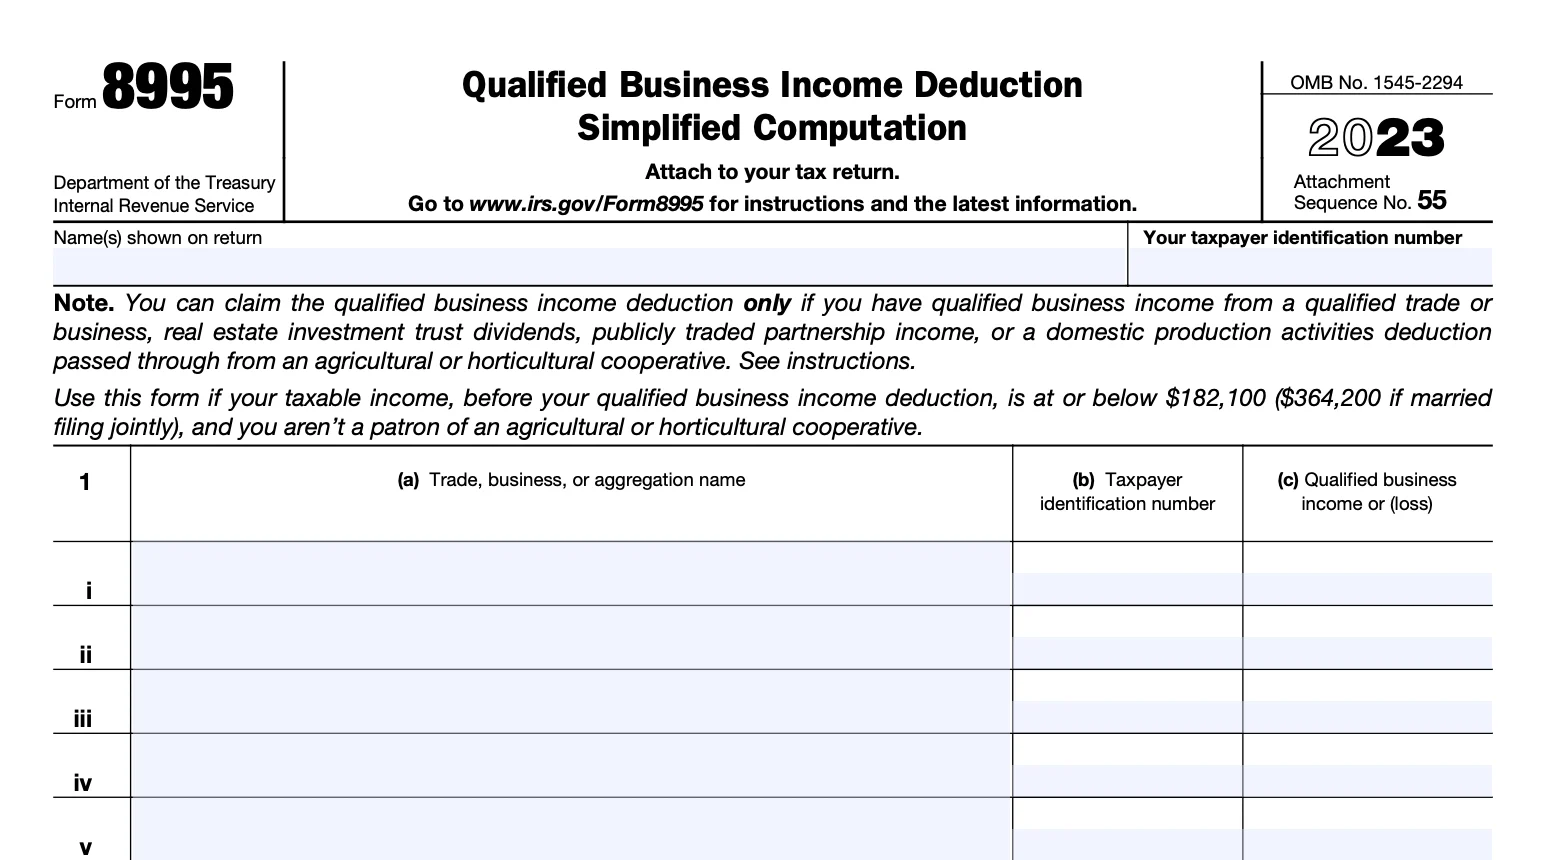
There are two forms you can use to apply for your QBI deduction: Form 8995 and Form 8995-A.
For 2025 returns, use Form 8995 if your taxable income before the QBI deduction is:
$197,300 or less ($394,600 or less if married filing jointly)
You aren't a patron of an agricultural or horticultural cooperative.
Otherwise, use Form 8995-A:
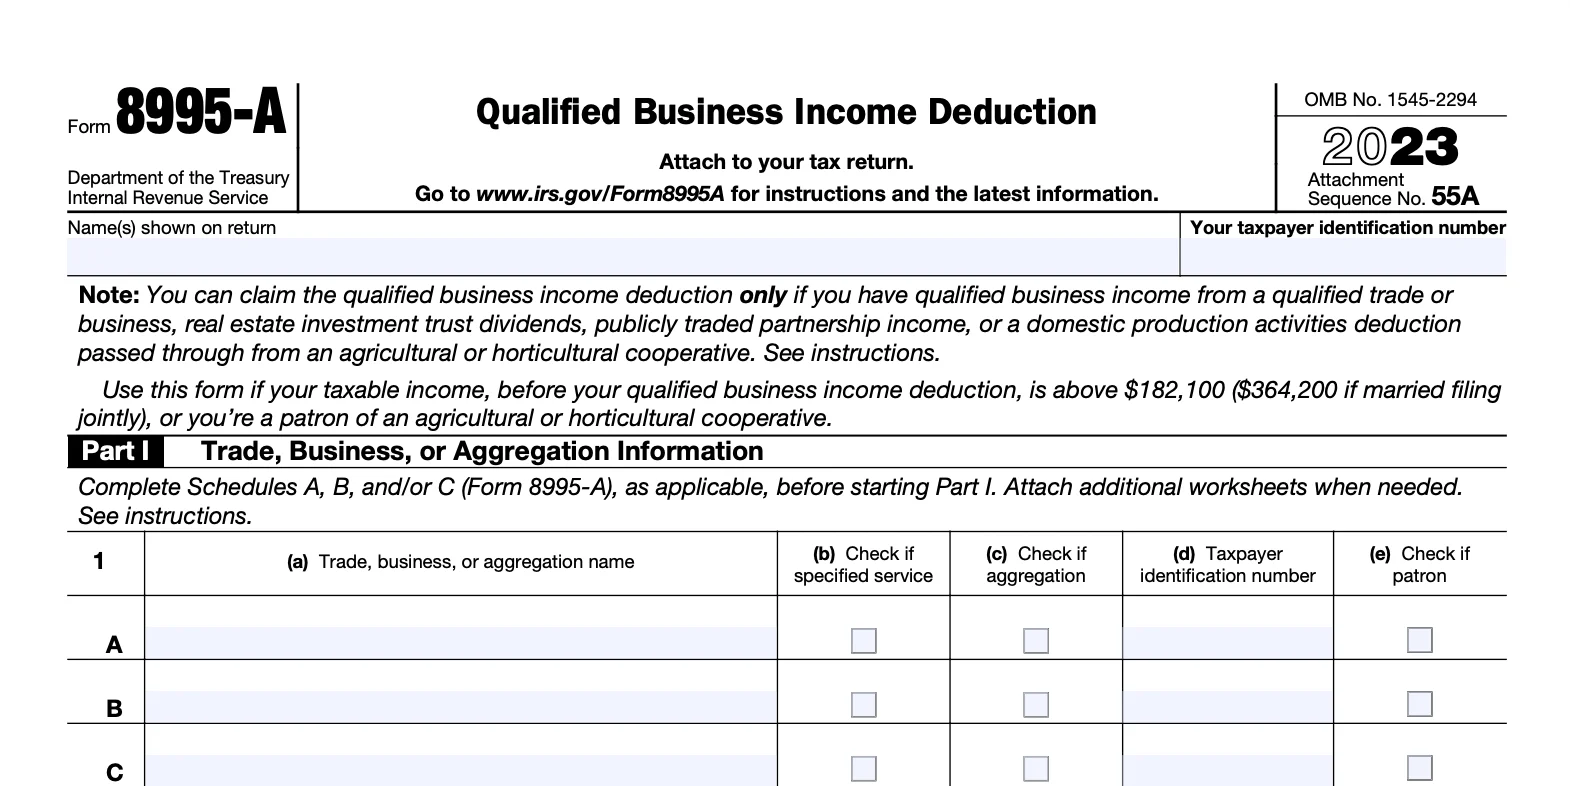
And that’s it! Both of these forms have worksheets that will help you determine the amount of QBI deduction you’re eligible for. And once you’re done filling the relevant form out, make sure to attach it to your tax return when you send it off to the IRS.
Hopefully, you’re a little clear now about how the QBI deduction works — and feel ready to maximize it to your full advantage. If you still have questions, the IRS has a pretty thorough Q&A page dedicated to the deduction.
And if you’re looking for simpler explanations of complicated tax topics, our Keeper tax assistants are here for you! Download the app, and text your questions. You’ll get back an answer in plain English.
Justin is an IRS Enrolled Agent, allowing him to represent taxpayers before the IRS. He loves helping freelancers and small business owners save on taxes. He is also an attorney and works part-time with the Keeper Tax team.
View full bio
Scott Levy grew up in Miami, Florida, the son of a CPA and Tax Attorney. You could say taxes were in his blood. He's been a licensed CPA since 2011 with a Bachelors in Accounting, and a Master's in Applied Economics and Data Intelligence. Over the years, Scott has worked with a large variety of clients from different walks of life. From bartenders to CEOs, Scott has helped them all maximize their tax savings and plan for their futures.
View full bio5 sources
- Tax Cuts and Jobs Act: A comparison for businesses · irs.gov
- Qualified business income deduction · irs.gov
- Tax Cuts and Jobs Act, Provision 11011 Section 199A · irs.gov
- 2025 Form 8995 · irs.gov
- 2025 Form 8995-A · irs.gov
Keeper’s tax guides are built on primary sources: the tax code, IRS forms, instructions and publications, and state tax agency guidance. We link to external sources where appropriate and check figures against the tax year they apply to. This article was peer reviewed by a licensed tax professional (CPA or EA).
This article is for informational purposes only and isn’t tax, legal, or financial advice. Tax rules change and depend on your situation, so talk to a tax professional about yours.