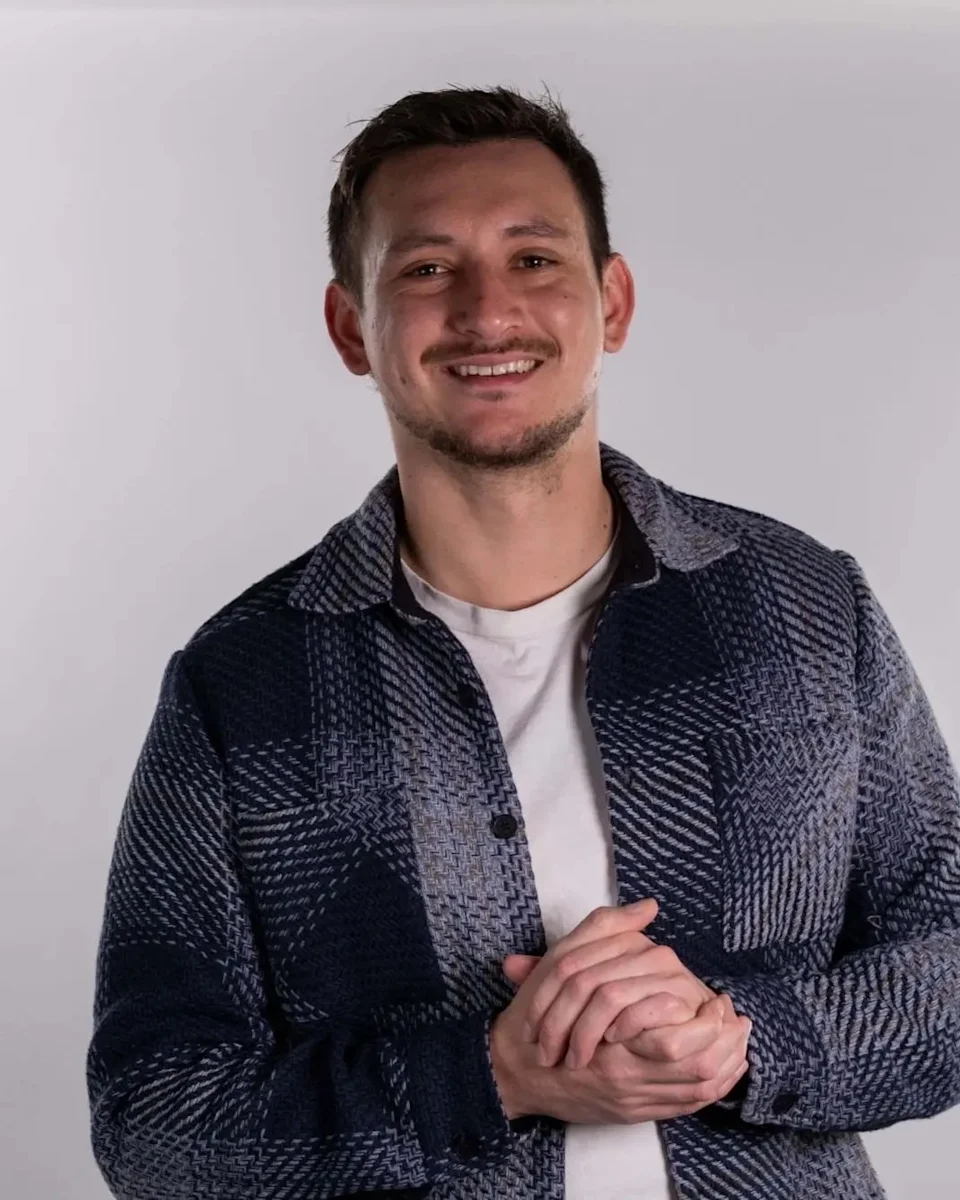
Successful to me would be leaving a good inheritance for my daughters.
Roland went from cutting hair in San Francisco for about $80K a year to nearly $900K in gross commissions selling Bay Area homes. What he’s really building is a head start for his two daughters.
Income streams
- Real estate sales (commission)
- House flipping
Tax setup
- Earns 100% commission income, with no steady paycheck
- Saves a cushion from every good month for his tax bill
- Has big write-offs to track, like MLS and realtor dues, platforms, office expenses, and filming gear
- Runs his business through an S-Corp and pays himself a salary
What did suddenly owning a house at 19 teach him?
Roland grew up in a middle-class household in Benicia, California, with his mom and stepdad. At 19, a sudden golden opportunity fell into his lap. His aunt’s house was nearing foreclosure. On his mom’s advice, he and his older brother decided to use the money they’d saved to modify the loan and put it in their names.
Roland pictured parties and living on his own. The reality wasn’t as glamorous. Saddled with a mortgage, he ended up juggling two entry-level service jobs as a restaurant server and Panera worker to pay the bills.
Owning a home forced him to get financially sturdy fast. It also showed him something most 19-year-olds never see. He knew what they owed on the loan, and he could see what the house was worth.
I knew how much our loan balance was and I saw what that home value estimate was showing me the house was worth, and I was like, “Oh, that’s crazy.”
The gap between the two was equity, and it was his first lightbulb moment about real estate.
How does a barber end up selling homes?
Working two jobs and paying a mortgage made college feel out of reach, so Roland got his barber’s license instead. He cut hair in San Francisco for two to three years, earning about $80,000 a year, plus tips, and saved as much as he could.
He never forgot the gap he’d spotted at 19 between what the house was worth and what they owed on it. He wanted to learn how to turn that equity gap into a business: buy a home, add value, and sell it for more.
The woman who had helped modify his aunt’s loan flipped houses for a living. Once he had enough saved, he called her.
Hey, I have some money saved. I want to do what you do.
He shadowed her, invested with her, did a flip alongside her, and then a couple on his own. He got his real estate license mostly to keep up with the terminology. Then he helped a friend buy a home, and that was it.
He didn’t quit being a barber overnight. He gradually cut back to four days a week, then three, then two, until real estate could carry him.
“For how low my expenses were, I was able to really save and be diligent. So that’s how I was able to invest in my first flip and then just compounded from there.”
Real estate was slow moving at first
Real estate is commission only. After his first sale, it was six to eight months before his next one. He spent almost a year working under an agent who wasn’t active and couldn’t teach him much.
It’s so weird to get over getting paid on time every two weeks or every week versus having it be so spotty between weeks and months.
Then came the most expensive mistake of his life. On a flip guided by a mentor he trusted, they tried to add on to the house without permits. The city red-tagged the project and stopped all work. Roland lost about $100,000 of his own money while he was still barely making sales.
That was a super low, brutal time in my life, and [I’m] really glad that I didn’t let that define me or have me stop.
His lesson: do things the right way, and remember that reliance on a mentor can be a pro and a con. You have to trust your judgment, too.
How did the business take off?
The turning point came in 2021 or 2022, when a single flip made him about $350,000. With his sales on top, it was roughly a $500,000 year. Then, his commissions from his real estate business started climbing: about $600,000 in gross commission income in 2023 or 2024, then nearly $900,000 last year, his best year yet.
What changed was attention. Roland figured out how to market on social media. He hated sitting at open houses, waiting for prospective buyers to show up, so he crafted another way to get in front of people: TikTok and Instagram. His first videos felt cringey. And then came the breakthrough: home tours.
Why wouldn’t I just go into these crazy beautiful homes and give people an inside look at them?
He films everything himself with a gimbal and a plug-in mic that cost about $100 each, plus CapCut and Edits. Now buyers fill out his forms straight from TikTok and Instagram or reach out from YouTube, and he’s hired an inside sales agent to follow up on the leads.
Turning real estate into a family business
Roland’s mom never settled into one career. She worked a series of jobs while he was growing up. Watching his business take off, she told him she wanted to get licensed too.
He warned her he wouldn’t be a good mentor, so she got licensed and started out at a brokerage in Benicia. When his own business grew past what he could handle on his own, he asked for her help.
Today they split everything 50/50. She runs the open houses and much of the back end. He handles the camera and the appointments. Her help is what buys him time with his wife and two daughters.
Having someone that works as equally as hard as you, I think, is the biggest secret.
Would he do it all again?
If he was offered the same salary, he’d stay his own boss, because he can see how much more is possible. Like a lot of people working for themselves, he’s learned to treat income as a wave, saving in the good months to ride out the slow ones.
How does he handle taxes?
Roland has used a CPA from day one and now pays about $300 a month for it. In his first few years he barely earned enough to owe much. Now that his income is consistent, the bills are big, and he’s always kept a cushion so a tax bill never catches him short.
He’s also candid about what slips. He knows he should be paying quarterly estimated taxes and admits he isn’t this year. He has a long list of write-offs, from MLS and realtor association dues to the platforms he uses, office expenses, and equipment, that he wants a better grip on. And as his income grew, he and his mom each set up an S-Corp, so each of them pays themselves a salary.
Taxes, with running your own business, is a whole other system that it’s so easy to neglect because it’s not sexy. It’s not fun.
What is it all for?
Roland sells everything from a $350,000 condo in Berkeley to a $1.8 million home, and he sees the Bay Area’s inequality up close. More and more young buyers are getting help from family, through an inheritance or a parent’s ADU, and he worries the AI boom is speeding that gap up.
Anytime you see a young person buying a home, know in the back of your head, highly likely that that’s coming from some family help.
He bought his first home at 19 without that help, and he still remembers how much it narrowed his choices having to pay a mortgage. That’s the freedom he wants to hand his daughters: a couple of paid-off homes, so they never have to pick a path just to cover the rent.
Successful to me would be leaving a good inheritance so my daughters could do anything creatively that they love to do.
How to build a real estate business like Roland
Save a cushion before you jump
Expect to make little or nothing for a while. Roland went six to eight months between his first and second sales, and his barber savings carried him.
Taper off your steady job
He cut back to four days a week behind the barber’s chair, then three, then two, and only went full time once real estate could cover his bills.
Lean on mentors, but trust your own judgment
A mentor got him into flipping and taught him the business. Following that same mentor’s guidance on one flip also cost him $100,000. Learn everything you can from people who are further along, then pressure-test every big decision yourself.
Market where the attention is
Being good at your job isn’t enough anymore. Instead of sitting at open houses, Roland films home tours for TikTok, Instagram, and YouTube with about $220 of gear. Test formats until one resonates, repeat it, and keep trying new platforms, because attention comes in waves.
Buy back your time
Once leads outgrew him, he brought on an inside sales agent and teamed up with his mom, so he could stay consistent without burning out.
Plan for taxes on day one
Commission income comes with no tax withheld. Earning it means:
- Tracking business expenses as you spend
- Setting aside money for self-employment tax
- Paying estimated quarterly taxes
- Looking at an S-Corp once your profit grows
Roland teaches you how to make more. Keeper helps you keep more of it.
Every money move comes with a tax catch. Here’s how to plan for each one.
- His moveFlips housesThe tax catch
Profit on a home you buy and sell within a year is taxed at ordinary income rates, and when flipping is your business, it can owe self-employment tax too.
Keep more- Keep records of every renovation, permit, and holding cost. They lower your taxable profit.
- If a flip loses money, those records help you claim the loss.
- His moveEarns commission on home salesThe tax catch
Commission checks arrive with no tax withheld, and months can pass between closings.
Keep more- Set aside a percentage of every commission check.
- Pay estimated quarterly taxes, or risk underpayment penalties.
- In a record year, the safe harbor rule protects you from penalties if you pay at least as much as last year’s tax (110% once your income passes $150,000).
- His moveReinvests in marketing and his teamThe tax catch
Business costs you don’t claim mean paying income tax and 15.3% self-employment tax on money you already spent.
Keep more- Write off MLS and realtor association dues, lead and CRM platforms, and marketing.
- Track filming gear like his gimbal and mic as business equipment.
- Deduct what you pay team members, like his inside sales agent.
- Log the miles you drive to showings and listings.
- His moveHit nearly $900K in gross commissionsThe tax catch
As a sole proprietor, all of your business profit owes 15.3% self-employment tax, up to the yearly Social Security wage cap, plus 2.9% Medicare on everything above it.
Keep more- That’s why he and his mom each set up an S-Corp: they pay themselves a reasonable salary, and the rest of the profit avoids payroll taxes.
- The IRS expects that salary to match what you’d pay someone else to do the job. Set it too low and you risk back taxes and penalties.
- His moveSplits the business 50/50 with his momThe tax catch
Splitting commissions across two businesses means two sets of payroll, tax returns, and books, and each share has to land in the right company.
Keep more- Give each person their own S-Corp, like Roland and his mom, so each pays tax only on their half.
- Put the split in writing. If one company passes the other’s share along, record it as a business expense so the same dollars aren’t taxed twice.
- Each S-Corp files its own Form 1120-S and runs its own payroll. In California, each also owes a 1.5% franchise tax, with an $800 minimum.
- His moveWants to leave paid-off homes to his daughtersThe tax catch
How you pass on a home changes your kids’ tax bill when they eventually sell it.
Keep more- If your kids inherit a home, its tax value resets to what it’s worth when you pass away. Buy for $300K, pass it on at $1M, and they could sell for $1M with no tax on the growth.
- If you give them the home while you’re alive, they keep your original $300K value, so selling for $1M could mean paying tax on $700K of growth.
- Talk to an estate planner before you put a home in your kids’ names.
General information, not tax, legal, or investment advice. Limits and thresholds change every year.