The home office deduction: who qualifies and how to claim it

 Sarah York, EASarah is an Enrolled Agent with the IRS and a former staff writer at Keeper. In 2022, she was named one of CPA Practice Advisor’s 20 Under 40 Top Influencers in the field of accounting. Her work has been featured in Business Insider, Money Under 30, Best Life, GOBankingRates, and Shopify. Sarah has spent nearly a decade in public accounting and has extensive experience offering strategic tax planning at the state and federal levels. Her clients have come from a wide range of industries, including oil and gas, manufacturing, real estate, wholesale and retail, finance, and ecommerce, and she has handled tax returns for C corps, S corps, partnerships, nonprofits, and sole proprietorships. In her spare time, she is a devoted cat mom and enjoys hiking, painting, and overwatering her houseplants.
 Krislyn ChanKrislyn is Chief Growth Officer at Keeper. At Keeper, she strives to make expert-level tax strategies that used to require a traditional CPA accessible to all. Prior to Keeper, she was at Curology, where she helped bring custom, prescription-grade skincare out of the dermatologist's office to millions of faces.

Key takeaways
- The home office deduction is for self-employed people, including side hustlers. Employees with only W-2 income can’t claim it.
- Your office has to be used regularly and only for your business, and it has to be your main place of business. Doing your billing, bookkeeping, or scheduling there counts.
- The simplified method is $5 per square foot, up to $1,500. The actual expenses method is your business-use share of rent or mortgage interest, utilities, insurance, and more, and is often bigger.
- It lowers your income tax and your self-employment tax, but it can’t be more than your business’s profit.
- Your home office is one of many write-offs. Keeper connects to your bank accounts and cards, automatically flags the business expenses you can deduct, like your phone, software, and work travel, and tracks them all year. Find your write-offs, and a tax pro reviews your return before it’s filed.
What is the home office deduction?
The home office deduction lets self-employed people who work from home write off part of what they spend on their home. If you paid for an office somewhere else, you could deduct the rent. This deduction treats the part of your home you use for business the same way.
Renters and homeowners can both claim it, whether you live in an apartment, a condo, a house, or a mobile home. It goes on Schedule C, so it lowers both your income tax and your self-employment tax.
Who qualifies for the home office deduction?
You have to meet three requirements:
- You have self-employment income.
- You use the space regularly and only for your business.
- The space is your principal place of business.
Check if you qualify
Answer four quick questions.
Question 1 of 4
Do you have self-employment income, like freelance, 1099, or side-gig work?
1. You have self-employment income
The home office deduction is a business write-off. You qualify if you work as a freelancer, independent contractor, gig worker, or small business owner, and it’s fine if that work is a side hustle. You don’t need to get a 1099: cash or app payments for your own business count too.
Employees can’t deduct a home office, even if they work from home every day. That rule was set to expire after 2025, but the 2025 tax law made it permanent. If you have both W-2 and self-employment income, you can claim it for the self-employed work you do at home.
Own an S corp? You’re an employee of your company, so you can’t claim it on Form 8829. Your S corp can reimburse you for the business share of your home costs under an accountable plan instead.
2. You use the space regularly and only for business
Your office doesn’t need to be a separate room. A spare room, a converted garage or basement, a studio, or a desk area in the corner of your bedroom can all count, as long as it’s a clearly separate space.
Only for business means exactly that. If you also use the space for personal things, like a kitchen table you eat at or a desk your kids do homework at, it doesn’t qualify. A guest room that doubles as your office doesn’t count either.
Regularly means you use it on an ongoing basis, not just once in a while. The IRS doesn’t set a minimum number of hours. You don’t have to use it all year: if you start or stop your business partway through the year, you can deduct the months you used it.
There are two exceptions to the “only for business” rule:
- Storing inventory or product samples. If you sell products, like on Etsy or Amazon, and your home is your business’s only fixed location, you can deduct a storage space you use regularly for inventory or samples, even if you also use it for personal things. This covers products you sell, not tools or equipment.
- Daycare. If you run a licensed daycare at home, the space doesn’t have to be used only for business, but you figure the deduction differently. See IRS Publication 587.
3. It’s your principal place of business
Your home office can be your principal place of business in any of these ways:
- It’s where you do most of your work.
- It’s where you do your admin work, like billing clients, keeping your books, ordering supplies, or scheduling, and you don’t have another fixed location where you do much of that work.
- You regularly meet clients or customers there in person, even if you also work somewhere else. A massage therapist who sees clients at home and also works shifts at a spa can still qualify.
- It’s a separate structure, like a detached studio or workshop, used only for your business.
The admin rule is the one people miss. A plumber who spends the day at client sites, or a rideshare driver who works from their car, can still qualify if they handle their invoices, bookkeeping, and scheduling from a dedicated desk at home. Working at a coffee shop now and then, or doing a little admin work elsewhere, doesn’t disqualify you.
An office at your W-2 job doesn’t count against you either. It’s not a location of your own business.
What can you deduct?
With the actual expenses method, your home office deduction can include:
- 🏠 Rent
- 🏦 Mortgage interest and property taxes
- 💡 Utilities, like electricity, gas, water, and trash
- 🛡️ Renters or homeowners insurance
- 🔐 HOA fees and a home security system
- 🔧 Repairs and maintenance, like plumbing, electrical, or AC repairs
- 🧹 Cleaning services for the whole home
- 📉 Depreciation, if you own your home
For quick reference, use our home office cheatsheet (or the print-friendly version).
Direct vs. indirect expenses
How much of each cost you can deduct depends on what it’s for:
- Indirect expenses are for your whole home, like rent, utilities, and insurance. You deduct your business-use percentage of them.
- Direct expenses are only for your office, like painting it or repairing its window. You deduct 100% of them.
- Unrelated expenses only benefit the rest of your home, like lawn care or painting your living room. You can’t deduct them.
Bigger projects that improve your home, like a new roof or remodeling your office, aren’t deducted all at once. You depreciate the business share of them over time.
What’s not part of the home office deduction
Some work-from-home costs are deducted separately on Schedule C instead. They don’t need a qualifying home office:
- 📶 Internet and phone: deduct the business-use share of your internet and cell phone bills.
- 🪑 Furniture and equipment: a desk, chair, computer, studio lights, or a sound system you use for work.
- 💻 Supplies and software you use for your business.
Keeper scans your bank and card purchases for all of these, along with your home costs, so you don’t have to dig through statements at tax time.
Track and claim every eligible deduction with Keeper
The #1 tax app for freelancers, gig workers, and self-employed filers.
Get started free
How to calculate your home office deduction
There are two ways to figure it. You can use either one, and you can switch from year to year.
The actual expenses method
First, find your business-use percentage: your office’s square footage divided by your home’s. Then multiply your indirect expenses by that percentage and add your direct expenses.
Say you rent a 900 sq ft apartment for $800 a month, and your desk area takes up 100 sq ft. Your business-use percentage is 11.1%, so you can deduct about $89 of your rent each month, or $1,067 for the year. The same percentage applies to your utilities, insurance, and other costs for the whole home.
The actual expenses method has two more advantages:
- Depreciation. If you own your home, you can deduct part of its cost each year. Here’s how real estate depreciation works.
- Carryover. If your deduction is more than your business’s profit, you can carry the rest forward to future years.
If you moved or changed your setup during the year, figure each home separately for the months you used it, with a separate Form 8829 for each.
The simplified method
The simplified method skips the expense tracking. You get $5 per square foot of office space, up to 300 square feet, for a maximum of $1,500. In the example above, the 100 sq ft desk area would be worth $500. Read more about when to use the simplified home office deduction.
- You don’t deduct depreciation, so there’s nothing to pay back when you sell your home.
- If you own and itemize, you still deduct your full mortgage interest and property taxes on Schedule A.
- Any amount over your business’s profit is lost. It doesn’t carry forward.
- If you used it for only part of the year, you use your average monthly square footage. And if you had offices in more than one home, you can use it for only one of them.
Which method should you use?
The actual expenses method is often bigger, especially if your rent or mortgage is high, your office takes up a large share of your home, or your office is over 300 square feet. The simplified method can make sense for a small office, low housing costs, or if you want to avoid depreciation. Use the calculator at the top of this page to compare both. If you track your expenses by hand, our free home office deduction worksheet can help.
Your deduction can’t be more than your profit
The home office deduction can’t create a business loss. It’s limited to your business’s profit before the home office deduction. For example, if your business earned $5,000 and had $4,600 of other expenses, your home office deduction can be no more than $400.
With the actual expenses method, the rest carries forward to next year. With the simplified method, it’s lost.
How to claim the home office deduction
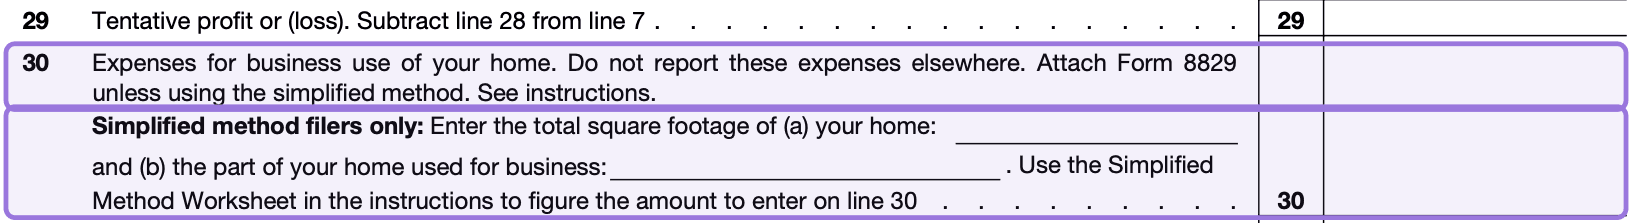
With the simplified method, you figure the deduction right on Schedule C, line 30. With the actual expenses method, you fill out Form 8829, “Expenses for Business Use of Your Home,” and carry the total to Schedule C. Here’s how, following a freelancer named Joe. The screenshots are from the 2025 forms, the latest versions the IRS has released.
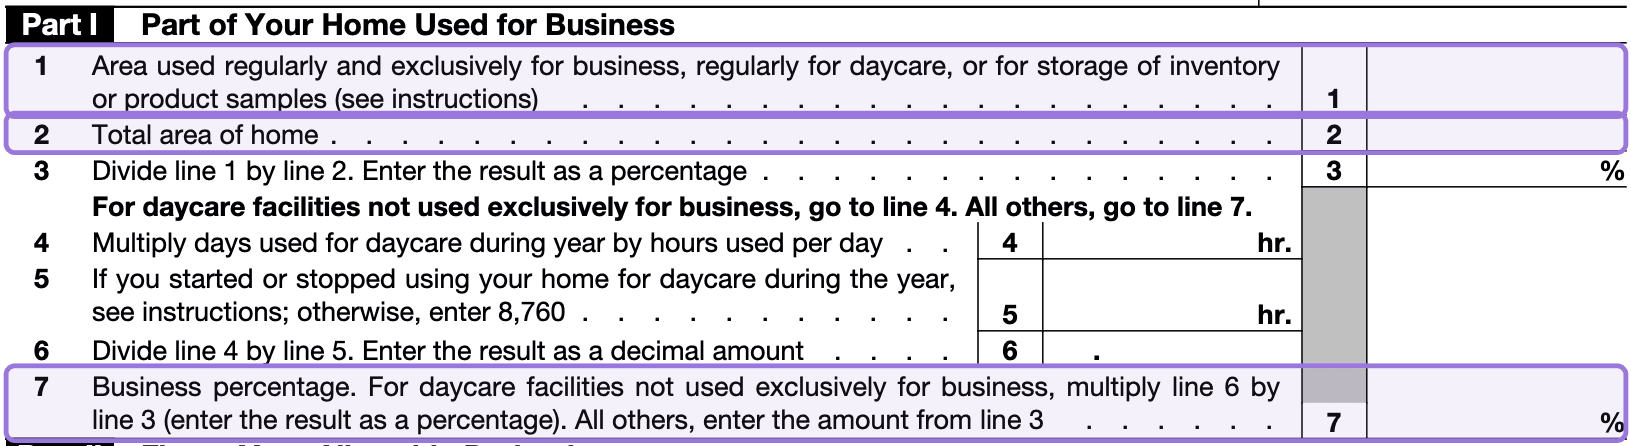
Step 1: Find your business-use percentage (Part I of Form 8829)
On line 1, enter your office’s square footage. On line 2, enter your home’s total square footage. The form divides the two to find your business-use percentage, which carries down to line 7. Skip lines 4 to 6 unless you run a daycare. Keep a note of how you measured.
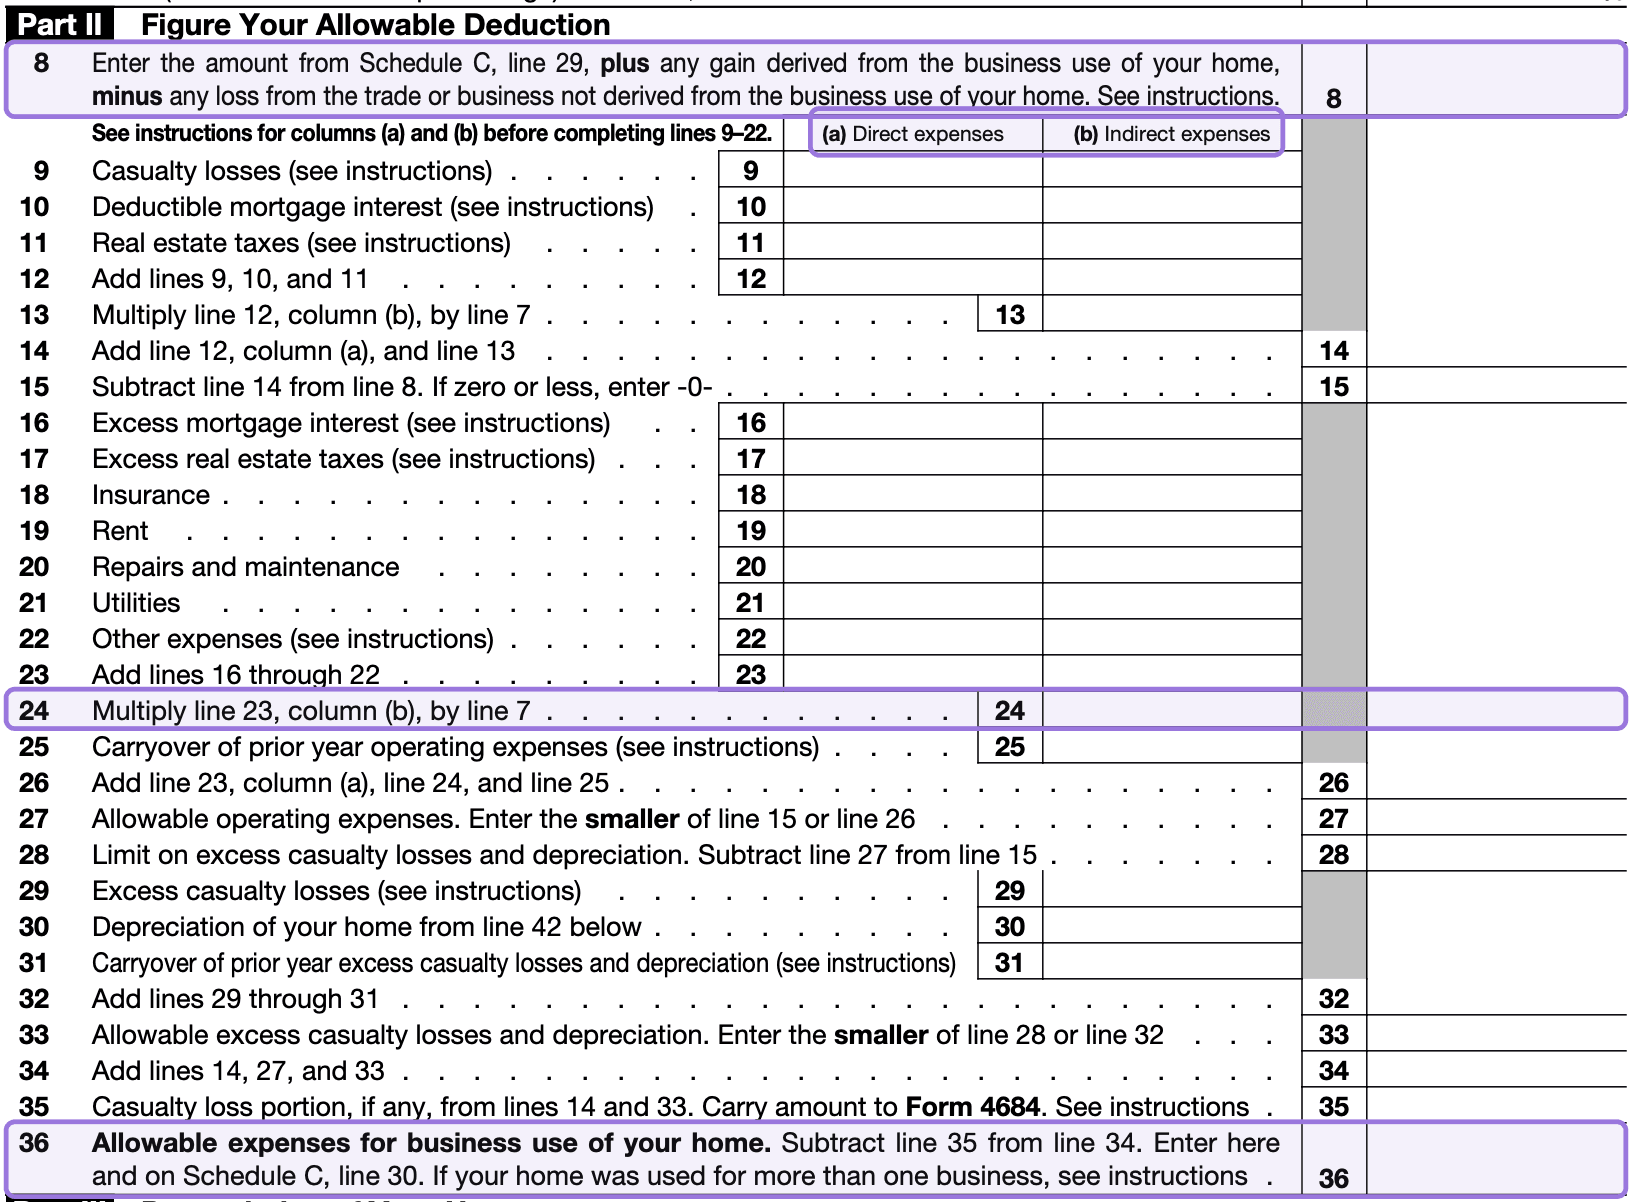
Step 2: Enter your expenses (Part II of Form 8829)
On line 8, enter your business’s profit from Schedule C, line 29. That’s your income minus your other business expenses. If it’s zero or less, you can’t take a deduction this year, but with this method you can carry it forward. Joe’s profit is $5,000.
Then list your expenses in two columns: direct expenses for the office only in column (a), and indirect expenses for your whole home in column (b). The form applies your business-use percentage to column (b) and adds column (a). Costs without their own line go on line 22, “Other expenses.”
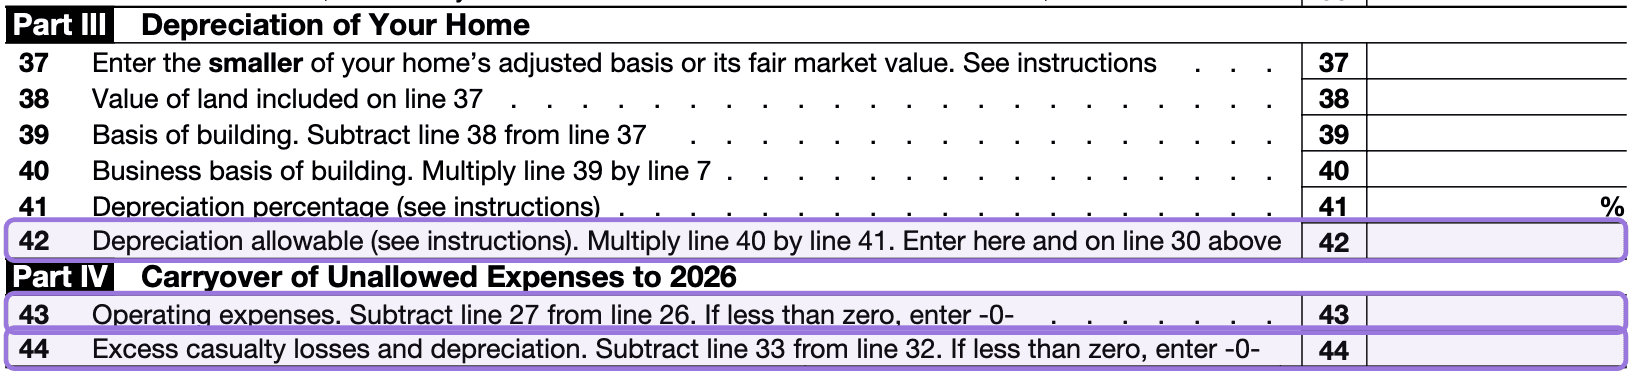
Step 3: Add depreciation and carryovers (Parts III and IV)
If you own your home, figure depreciation here, based on the lower of what you paid for it (plus improvements) or its value when you started using the office, not counting land. Renters can skip this part. Part IV tracks any amount you couldn’t use this year, so you can carry it forward. See the IRS instructions for the depreciation math, or let Keeper handle it when you file.
Step 4: Carry the total to Schedule C
Enter the total from line 36 of Form 8829 on line 30 of Schedule C.
Step 5: See what you saved
Say Joe’s home office deduction comes to $1,400. That lowers his profit from $5,000 to $3,600, which cuts his self-employment tax by about $198. He saves income tax too, at his tax bracket rate, on most of the deduction.
Selling your home after claiming a home office
If you used the actual expenses method and claimed depreciation, that depreciation is taxed when you sell your home, at a rate of up to 25%. This applies even if the rest of your gain is covered by the home sale exclusion. If your office was a separate building, like a detached studio, part of your gain may not qualify for the exclusion at all. The simplified method doesn’t include depreciation, so it avoids this.
Keep good records
The home office deduction is common and legitimate. Just be accurate and keep records that show you qualify and how you figured it:
- Your office’s measurements and your home’s total square footage, from a listing or your lease
- Photos of your office and how it’s set up
- Receipts and statements for your home expenses
- If you own, what you paid for your home and any improvements
Keep most records for at least three years after you file. Keep records of your home’s cost and any depreciation until at least three years after you file the return for the year you sell it.
6 sources
- Publication 587, Business use of your home · irs.gov
- Instructions for Form 8829 · irs.gov
- Simplified option for home office deduction · irs.gov
- Rev. Proc. 2013-13: simplified method · irs.gov
- Topic no. 509, Business use of home · irs.gov
- Publication 523, Selling your home · irs.gov
This article is for informational purposes only and isn’t tax, legal, or financial advice. Tax rules change and depend on your situation, so talk to a tax professional about yours.




 By Justin W. Jones, EA, JD