1099 taxes in 2026: a guide for the self-employed

 Sarah York, EASarah is an Enrolled Agent with the IRS and a former staff writer at Keeper. In 2022, she was named one of CPA Practice Advisor’s 20 Under 40 Top Influencers in the field of accounting. Her work has been featured in Business Insider, Money Under 30, Best Life, GOBankingRates, and Shopify. Sarah has spent nearly a decade in public accounting and has extensive experience offering strategic tax planning at the state and federal levels. Her clients have come from a wide range of industries, including oil and gas, manufacturing, real estate, wholesale and retail, finance, and ecommerce, and she has handled tax returns for C corps, S corps, partnerships, nonprofits, and sole proprietorships. In her spare time, she is a devoted cat mom and enjoys hiking, painting, and overwatering her houseplants.
 Reviewed byScott LevyScott Levy grew up in Miami, Florida, the son of a CPA and Tax Attorney. You could say taxes were in his blood. He's been a licensed CPA since 2011 with a Bachelors in Accounting, and a Master's in Applied Economics and Data Intelligence. Over the years, Scott has worked with a large variety of clients from different walks of life. From bartenders to CEOs, Scott has helped them all maximize their tax savings and plan for their futures.
 Krislyn ChanKrislyn Chan is a consumer subscription growth leader who has spent her career making premium services affordable and accessible. As Chief Growth Officer at Keeper, she drives growth for a platform that pairs AI with licensed tax professionals to help self-employed people keep more of what they earn. She has written more than 50 Keeper guides on tax strategy for freelancers, independent contractors, and small business owners. Previously, Krislyn was at Curology, where she helped turn dermatologist-grade custom skincare into a direct-to-consumer subscription used by millions.

Key takeaways
- 1099 income is subject to two federal taxes: 15.3% self-employment tax on 92.35% of your profit and 10% to 37% federal income tax. Most states add their own income tax on top.
- Self-employment tax applies to 92.35% of your profit. The 12.4% Social Security tax only applies to your first $184,500 of earnings in 2026; the 2.9% Medicare tax applies to all of it.
- Set aside 20–25% of your profit if your state has no income tax, and 25–30% in most other states, in a high-yield savings account. Federal tax alone runs from 18.6% of profit at $40,000 to 26.7% at $200,000 for a single filer, and your state adds more.
- Pay quarterly estimated taxes if you expect to owe $1,000 or more for the year, including self-employment tax. 2026 payments are due April 15, June 15, and September 15, 2026, and January 15, 2027. Get your amounts with the quarterly tax calculator.
- You should expect a 1099 form once you pass the 2026 thresholds: a 1099-NEC or 1099-MISC when a client pays you $2,000 or more (up from $600), or a 1099-K when a payment app or marketplace pays you more than $20,000 across more than 200 payments. You owe tax on your income whether or not you get a form.
How much tax do you pay on 1099 income?
These tables show estimated 2026 federal tax on self-employment profit, the amount left after business expenses. They assume this is your only income, you take the standard deduction, and you have no kids or tax credits.
Single filer, 2026
| 1099 profit | Total tax | % of profit | Self-employment tax | Federal income tax |
|---|---|---|---|---|
| $40,000 | $7,427 | 18.6% | $5,652 | $1,775 |
| $60,000 | $12,037 | 20.1% | $8,478 | $3,559 |
| $80,000 | $16,647 | 20.8% | $11,304 | $5,344 |
| $100,000 | $22,365 | 22.4% | $14,130 | $8,235 |
| $150,000 | $37,608 | 25.1% | $21,194 | $16,413 |
| $200,000 | $53,431 | 26.7% | $28,234 | $25,196 |
Married filing jointly, one self-employed spouse, 2026
| 1099 profit | Total tax | % of profit | Self-employment tax | Federal income tax |
|---|---|---|---|---|
| $40,000 | $6,050 | 15.1% | $5,652 | $398 |
| $60,000 | $10,363 | 17.3% | $8,478 | $1,885 |
| $80,000 | $14,854 | 18.6% | $11,304 | $3,550 |
| $100,000 | $19,464 | 19.5% | $14,130 | $5,335 |
| $150,000 | $30,990 | 20.7% | $21,194 | $9,795 |
| $200,000 | $44,706 | 22.4% | $28,234 | $16,472 |
State income tax comes on top. At $80,000 of profit, it adds about $2,613 in California and nothing in Texas. Find your state’s 1099 tax calculator.
How 1099 income is taxed
When you work for yourself, no employer withholds taxes from your pay, so you figure and pay them yourself. Your net profit (1099 income minus business expenses) is taxed three ways:
- Self-employment tax: 15.3% on most of your profit (92.35% of it). That’s 12.4% for Social Security, on earnings up to $184,500 in 2026, plus 2.9% for Medicare with no cap. If your earnings top $200,000 ($250,000 married filing jointly), you pay an extra 0.9% Medicare tax on the amount over that. Estimate it with the self-employment tax calculator.
- Federal income tax: 10% to 37% on what’s left after three deductions: the $16,100 standard deduction ($32,200 married filing jointly), half of your self-employment tax, and the 20% QBI deduction.
- State income tax, in most states. Rates and rules vary a lot, from nothing in Texas and Florida to 1% to 12.3% in California (13.3% once taxable income passes $1 million).
Self-employment tax is the same Social Security and Medicare tax employees pay. An employer pays half of it for them. When you work for yourself, you pay both halves, which is why the IRS lets you deduct half of it from your income. To compare the two, try the 1099 vs. W-2 calculator.

Example: tax on $80,000 of 1099 income
Here’s how much federal tax a single self-employed person with $80,000 of profit and no other income would pay, step by step:
| Step | Amount |
|---|---|
| Self-employment tax: $80,000 × 92.35% × 15.3% | $11,304 |
| $80,000 minus half of self-employment tax | $74,348 |
| Income the IRS taxes: $74,348 minus the $16,100 standard deduction and $11,650 QBI deduction (20% of what’s left after the standard deduction, which is the cap that applies here) | $46,599 |
| Federal income tax | $5,344 |
| Total federal tax | $16,647 (20.8%) |
Self-employment tax is about two-thirds of the bill. It applies to almost all of your profit, so the main way to lower it is to deduct every business expense you’re entitled to.
What tax write-offs can I claim?
How to lower your 1099 tax bill
At $80,000 of profit, every $1,000 of business expenses you deduct cuts about $231 from your total tax. Common write-offs for self-employed people include:
- Your phone and internet, for the share you use for work
- Car expenses, using a set rate per mile or your actual costs (compare the two)
- A home office, if you use part of your home regularly and only for work (estimate yours)
- Software, equipment, and supplies you buy for your business
- Health insurance premiums you pay as a self-employed person
- Retirement contributions to a SEP-IRA or Solo 401(k)
Most of these are small purchases spread across a year of bank and card statements, which is where they get missed. See the full list of tax write-offs for self-employed people.
Track and claim every eligible deduction with Keeper
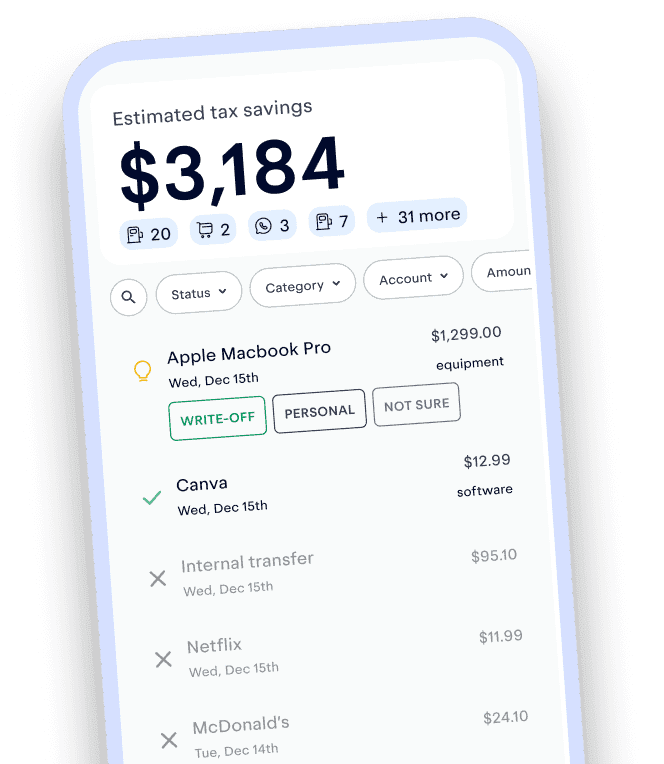
Keeper scans your accounts for write-offs and files your return — with tax pros reviewing every one.
Try it freeQuarterly estimated taxes for 2026
When you’re self-employed, no income tax or Social Security and Medicare tax is taken out of your pay, so the IRS expects you to pay as you earn through quarterly estimated taxes. You generally need to make quarterly payments if you expect to owe $1,000 or more for 2026, counting self-employment tax, beyond any tax already taken out of a paycheck.
| Payment | For income earned | Due date |
|---|---|---|
| 1st | January 1 to March 31, 2026 | April 15, 2026 |
| 2nd | April 1 to May 31, 2026 | June 15, 2026 |
| 3rd | June 1 to August 31, 2026 | September 15, 2026 |
| 4th | September 1 to December 31, 2026 | January 15, 2027 |
- To avoid a penalty for paying too little, pay at least 90% of this year’s tax or 100% of last year’s, whichever is less. This is called the safe harbor rule.
- Higher earners: if your income last year was over $150,000 ($75,000 married filing separately), you need to pay 110% of last year’s tax instead of 100%.
- Most states have their own quarterly payments, on similar dates. See quarterly taxes by state.
Get your payment amounts with the quarterly tax calculator, or see how to pay quarterly taxes.
What changed for 1099 workers in 2026
- Fewer 1099-NECs: clients only have to send one once they pay you $2,000 or more for payments made in 2026, up from $600.
- 1099-K stays at $20,000: payment apps and marketplaces send one once you receive more than $20,000 across more than 200 payments.
- A bigger standard deduction: $16,100 for single filers, $32,200 for married couples filing jointly, and $24,150 for heads of household.
- A higher Social Security cap: the 12.4% part of self-employment tax applies to the first $184,500 of earnings, up from $176,100.
- The QBI deduction is permanent. It was set to expire after 2025. Starting with 2026 returns, if you have at least $1,000 of qualified business income from a business you actively work in, your deduction is at least $400, even if 20% of your income would come out lower.
- A new deduction for tips: if you work in an occupation on the IRS’s tipped-occupation list, you may be able to deduct up to $25,000 of tips from 2025 through 2028. For self-employed workers, the deduction can’t exceed the net profit of the business the tips came from, the tips have to show up on a 1099-NEC, 1099-K, or 1099-MISC, and the deduction phases out above $150,000 of modified AGI ($300,000 married filing jointly). It lowers income tax, not self-employment tax.
Two year-end timing moves
You likely report income in the year you’re paid and expenses in the year you pay them. That means you can time some payments to your advantage, pushing income into next year or pulling deductions into this one to lower this year’s tax bill:
- Invoice in January instead of December. Money you receive on January 2 is taxed a year later than money you receive on December 31. This works best if you bill clients directly; gig apps pay on their own schedule.
- Pay January business expenses in December. If your rent, software, or other work bills are due early in the new year, paying them in December moves the deduction into this year.

These moves only shift timing. They help most in a year when your income is unusually high, or when you expect it to drop next year.
Which tax forms do 1099 workers use?
- Forms you receive: a 1099-NEC from clients, a 1099-K from payment apps and marketplaces, and sometimes a 1099-MISC for other payments like rent or prizes.
- Forms you file: Schedule C for your business income and expenses, Schedule SE for self-employment tax, and Form 1040, your regular tax return.
- Quarterly payments: Form 1040-ES, or pay online through your IRS account.
For a walkthrough, see how to file self-employment taxes step by step.
9 sources
- Topic no. 554, Self-employment tax · irs.gov
- Am I required to file a Form 1099 or other information return? · irs.gov
- The Working Families Tax Cuts: what gig economy workers should know · irs.gov
- Working Families Tax Cuts: individuals and workers · irs.gov
- Qualified business income deduction · irs.gov
- What the no tax on tips deduction means for you · irs.gov
- Estimated taxes · irs.gov
- Publication 505: tax withholding and estimated tax · irs.gov
- Contribution and benefit base · ssa.gov
Keeper’s tax guides are built on primary sources: the tax code, IRS forms, instructions and publications, and state tax agency guidance. We link to external sources where appropriate and check figures against the tax year they apply to. This article was peer reviewed by a licensed tax professional (CPA or EA).
This article is for informational purposes only and isn’t tax, legal, or financial advice. Tax rules change and depend on your situation, so talk to a tax professional about yours.