


Key takeaways
While you can't completely escape paying taxes on 1099 income, you may be able to lower your tax bill by taking advantage of deductions and being smart about tax planning.
You generally owe self-employment tax if your net earnings are $400 or more, even if you don’t receive a 1099.
Eligible business expenses can reduce both your income tax and self-employment tax.
The QBI deduction may let eligible freelancers deduct up to 20% of qualified business income.
Health insurance and retirement contributions may lower your income tax, but generally not your self-employment tax.
An S-Corp can reduce employment taxes for higher-earning freelancers, but the savings must outweigh payroll, filing, and administrative costs. Read our S-Corp guide for more information.
Every taxpayer wants to know that one secret IRS loophole: the one that will magically bring their tax payments down to zero, clear their pores, and water their lawn. Unfortunately, that particular secret doesn’t exist.
You generally cannot avoid tax on taxable 1099 income, but you may be able to lower your bill through legitimate business deductions and other tax breaks.
If your net earnings from self-employment are $400 or more, you generally owe self-employment tax. You must also report taxable income even when a client or payment platform does not send you a 1099.
But there are six tricks that freelancers, 1099 independent contractors, and other self-employed people can use to significantly lower their tax bill — and it’s all completely legit. In fact, the IRS specifically builds provisions for these situations right into the tax code. Welcome to the world of tax avoidance, the completely legal art of reducing, minimizing, and avoiding taxes!
Most freelancers overpay their taxes. Let’s make sure you’re not one of them.
Do you always have to pay taxes on a 1099?
Yes, you almost always get taxed on your 1099 income. If your net earnings from self-employment are $400 or more, you’ll have to file a return and pay self-employment tax, even if your total income is below the standard deduction. You can avoid paying quite a bit of tax on your freelance or small business earnings, but you can’t wriggle out of it all.
Why 1099 workers start paying taxes at $400
For most people, taxes only kick in if you earn more than the standard deduction. For the 2026 tax year, that’s $16,100 if you’re single, $32,200 if you’re married filing jointly, and $24,150 for heads of household.
So why only $400 for freelancers and contract workers? Because self-employment tax is separate from income tax. The standard deduction shields you from income tax, but it does nothing for the 15.3% self-employment tax, which kicks in once your net self-employment earnings reach $400. (That’s true of all self-employment income, whether it’s a part-time side hustle or a full-time career.)
What taxes do independent contractors pay?
Independent contractors commonly owe federal income tax and self-employment tax. State and local income or business taxes may also apply.
Self-employment tax funds Social Security and Medicare. The combined rate is generally 15.3%, consisting of 12.4% for Social Security and 2.9% for Medicare. That rate also generally applies to 92.35% of net earnings from self-employment, subject to the annual Social Security limit and additional Medicare tax rules at higher incomes.
When you work as a W-2 employee for a company, you automatically have 7.65% of your income withheld from your paycheck for taxes. This is known as the Federal Insurance Contributions Act, or FICA. At the same time, your employer is paying the IRS an additional 7.65%.
But when you work for yourself, there is no employer footing that half of the bill — you are your own employer. Which means you need to pay both halves, for a combined total of 15.3%. That is why taxes can feel more expensive when you move from a paycheck to independent work.
The good news is that the tax code gives business owners several legitimate ways to lower taxable income.
Which strategies lower which taxes?
Not every deduction affects your tax bill in the same way. Some reduce both income tax and self-employment tax. Others reduce only income tax. Let's take a look.
Strategy | Reduces federal income tax | Reduces self-employment tax |
|---|---|---|
Deduct eligible business expenses | Yes | Yes |
Deduct the employer-equivalent portion of self-employment tax | Yes | No |
Claim the qualified business income deduction (QBI) | Yes | No |
Deduct eligible self-employed health insurance premiums | Yes | No |
Make deductible retirement contributions | Yes | Generally no |
Elect S-Corp tax treatment | Generally no | Potentially |
Tax avoidance strategy #1: Write off all your business expenses
Okay, so we spill the beans on this “secret” all the time — but that’s because most people still don’t write off all the business expenses they qualify for! Even though it’s the best way to lower their self-employment tax.
Business expenses are usually the most direct way for a freelancer to lower both income tax and self-employment tax. They reduce the net profit reported on your Schedule C. Plus, you can claim these write-offs on top of the standard deduction, so don’t skip it.
A deductible expense generally must be ordinary and necessary for your business. In plain language, it should be common and accepted in your field as well as helpful and appropriate for your work.
Keeper pro tip: Personal expenses are not deductible. If something is used for both work and personal reasons, you can generally deduct only the business portion. Some expenses, including meals, vehicles, travel, and home offices, have additional rules and recordkeeping requirements.
If you’re not sure which expenses you can write off, try Keeper! We're an all-in-one app for your expense tracking and taxes. Keeper scans your bank and credit cards for qualifying tax deductions automatically, categorizes them, and files your taxes.
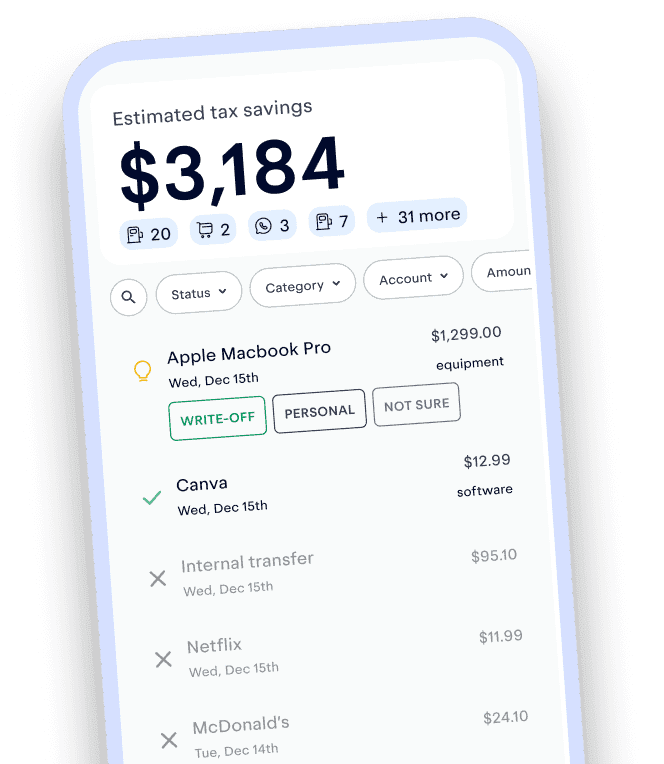
Track and claim every eligible deduction with Keeper
Keeper scans your accounts for write-offs and files your return — with tax pros reviewing every one.
Try it freeExample: how business expenses reduce self-employment tax
As an example, let’s say Rasheeda is a painter who’s started selling pet portraits on Etsy. After two years she’s taking in $40,000 a year in self-employment income. Not too shabby.
If Rasheeda reported the entire $40,000 as her net profit, she’d owe self-employment tax on 92.35% of it — about $5,650 — before she even gets to income tax.
Now, let’s say instead she downloads Keeper. She already knows that she should be writing off the cost of paint, brushes, and canvases — though sometimes she buys new colors on a whim and doesn’t remember to save her receipt.
That’s okay! In addition to noticing her purchase at Julio’s Art Mart and adding it to her deductions, Keeper also found:
📸 The new camera and lighting rig she bought to take pictures of her work
🌐 Her website hosting bill
🖱️ Her yearly subscription for Photoshop
📚 The art books she uses to study up for her work
☕ The times she met up for coffee with her other artist friends to brainstorm how to grow their businesses
💵 The money she paid her sister for packing and shipping her latest batch of portraits
📮 The packing and shipping supplies they used
🌲 The cost of her annual artist retreat
✈️ The business trip she made getting to and from the retreat site
🎨 A portion of her rent as a home office deduction, to cover the square footage she uses as a studio
You get the idea.
Now, instead of paying taxes on her full $40,000 earnings, she can write $10,000 off as business expenses and pay taxes on only $30,000. That alone cuts her self-employment tax by roughly $1,400, and because the same $10,000 also comes off her income for income tax purposes, her total savings are bigger
All businesses, big and small, get to take advantage of these savings. But did you know there are unique deductions available only to freelancers and other self-employed small business owners?
Tax avoidance strategy #2: Deduct your self-employment tax from your income tax
If this one is making you go, “Wait, that can’t be real” — let us assure you, it very much is.
Remember the justification the IRS uses to make you pay extra in FICA taxes: you needed to cover both the employer and the employee portion? Well, here’s where you get to use that same logic against them.
Because you are both your own employer as well as the employee, you get to deduct the employer-equivalent half of your self-employment tax (one-half of the total) as an adjustment to income. It lowers your income tax, not your self-employment tax.
We know, it sounds sneaky. But far from being tax evasion, this calculation is actually built right into your Schedule SE! The result flows straight from Schedule SE to Schedule 1 of your Form 1040, so if you file with tax software or with Keeper, it’s nearly impossible to miss. Just don’t count on the IRS to catch it for you if you skip it.
Tax avoidance strategy #3: Deduct up to 20% of your business income with the QBI deduction
Because this one has so many rules and exceptions to wrap your head around, most 1099 workers and other freelancers don’t realize that they’re missing out on a huge savings opportunity.
Introduced in 2018, and made permanent in 2025, the qualified business income deduction lets freelancers, independent contractors, and most small business owners deduct up to 20% of their qualified business income, without spending a dime to earn it.
Starting with 2026 returns, there’s also a new floor: if you have at least $1,000 of QBI from a business you actively run, your deduction is at least $400.
The QBI deduction can apply to income from sole proprietorships, partnerships, and S-Corporations. It does not reduce self-employment tax, and it is not always equal to 20% of your Schedule C profit.
Your deduction can be limited by:
Your total taxable income
The type of business you operate
W-2 wages paid by the business
Certain qualified property owned by the business
The overall limit based on taxable income minus net capital gain
For 2026, the wage, property, and specified-service-business limitations begin to phase in when taxable income exceeds $201,750 for most filers or $403,500 for married couples filing jointly. The phase-in ranges end at $276,750 and $553,500, respectively. Married taxpayers filing separately use the same thresholds as single filers.
Because deductions for self-employment tax, health insurance, and retirement contributions can affect QBI, the final calculation may be more complicated than multiplying profit by 20%. Read Keeper's complete guide to the QBI deduction or book a call with a tax professional at Keeper to see if the limitations may apply to you.
Tax avoidance strategy #4: Deduct your self-employed health insurance premiums
Again, when you’re a full-time W-2 employee, the company that employs you pays a portion of your health insurance plan. But that costs them money, so your employer gets to write off that expense.
Since you're technically a small business owner, if you pay for your own health coverage, you may be able to deduct eligible medical, dental, vision, and qualified long-term care insurance premiums for yourself, your spouse, and your dependents. Coverage for a child who was under age 27 at the end of the year may also qualify even if the child is not your dependent.
Be aware that self-employed health insurance deductions work a little differently than most business expenses. To start, you do not list it on your Schedule C with the rest of your write-offs. That’s because it lowers your income tax, not your self-employment tax.
Several important limitations apply:
The deduction is generally limited by the earned income from the business connected to the insurance plan.
You generally cannot claim it for a month when you or your spouse were eligible for a subsidized employer health plan.
Marketplace coverage and the premium tax credit can make the calculation more complicated.
Partners and more-than-2% S corporation shareholders must follow special payment and reporting rules.
Most 1099 workers have to foot a much larger bill to get good health insurance than people with 9-to-5 jobs. Being able to take such a hefty amount off your taxes — even if it only trims your income tax, not your self-employment tax — might help you sleep better!
Tax avoidance strategy #5: Put money in your retirement accounts
In addition to insurance expenses, you can also deduct contributions to your retirement account.
Self-employed individuals have the option to create a variety of retirement plans, including:
SEP IRAs
SIMPLE IRAs
Solo 401(k)s
Pre-tax contributions let you defer income tax on the money you put in until you withdraw it in retirement. Roth solo 401(k) contributions work the other way: no deduction now, tax-free withdrawals later.
How much you can defer will vary from plan to plan and year to year. The IRS updates their guidelines annually.
SEP-IRAs | Up to $72,000 |
SIMPLE IRAs | Up to $17,000 |
401(k)s | Up to $72,000 |
Deadlines and calculations vary by plan. If you also participate in a 401(k) through a W-2 job, your employee deferral limit generally applies across those plans. Compare your options in Keeper's solo 401(k) versus SEP IRA guide.
Tax avoidance strategy #6: Get paid through an S-Corp (if your income is high enough)
Think that corporate perks are only available to multi-billion-dollar media conglomerates? Think again!
Let’s check back in with Rasheeda. After a couple more years of hustling, her pet portraits have continued to grow, and now she’s netting an average of $150,000 a year.
At that income level, even with every deduction claimed, she’s still paying self-employment tax on nearly all of it — about $21,000 a year. So what does a business-savvy woman do? She forms an LLC and elects to be taxed as an S-Corp!
After filing the appropriate paperwork, Purrfect Pet Portraits is now a separate business entity. The business is still earning $150,000, but now Rasheeda pays herself a salary of $75,000 and takes the rest of the profit as a distribution.
How S-Corps can help you save on your taxes
Here’s where the benefits come in: Purrfect Pet Portraits now pays Social Security and Medicare taxes only on Rasheeda’s $75,000 salary — about $11,500 — rather than on the entire $150,000 of business income. The remaining profit passes through to her free of those taxes, saving her close to $10,000 a year before payroll and tax-prep costs.
Why you can’t set your S-Corp salary too low
Before you get too excited, let’s make one thing clear: You can’t set your personal salary at $1 to avoid paying FICA taxes on the rest of your business income.
Sadly, the IRS saw through that potential loophole immediately. They keep a pretty close eye on S-Corporations and require that all salaries be “reasonable compensation” for the work done.
It’s up to each business to determine what counts as “reasonable,” depending on the nature of your work. There’s no formula, but the IRS and the courts look at factors like:
How important the person is to business operations
How much time is being spent at their job
How much education and experience they bring to the table
In Rasheeda’s case, she’s the only employee. And without her artistic talents, Purrfect Pet Portraits would have to close up shop. It only makes sense for most of the business profits to go into her pockets.
When not to get an S-Corp
If you’re earning less than around $80,000 from your work, a formal business structure like an S-Corp might be more trouble than it’s worth.
If you don’t want to pay the fees
Here are two big ways in which an S-Corporation will cost you:
Legal fees to draw up formation documents and to register with all the state and federal agencies
Accounting fees to file your business tax returns and to maintain your books and records
Payroll fees to prepare quarterly payroll tax filings and a W-2 at year end
From setup fees to payroll taxes, S-Corporations are a big responsibility. For freelancers like Rasheeda — who make a comfortable, full-time income off their jobs — it may well be a solid investment, saving more than it costs. But not everyone is in the same position.
If you don’t want to deal with the hassle
Arguably the best thing about being a sole proprietor is that it keeps things simple. You can include your business taxes with your personal 1040 return.
As soon as you incorporate, though, you’ll need to complicate things. That means having to:
File a separate tax return for your business
Maintain financial records that include a balance sheet
How to claim tax savings on your 1099 income
If you want to save money with these tax strategies, you’ll need to fill out some forms. (No one’s idea of a good time, but it beats paying taxes!)
For a sole proprietor, the relevant forms commonly include:
Schedule C: Reports business income and deductible business expenses.
Schedule SE: Calculates self-employment tax and its deductible portion.
Schedule 1: Reports adjustments including the deductible portion of self-employment tax, eligible self-employed health insurance, and certain retirement contributions.
Form 7206: Calculates the self-employed health insurance deduction in applicable cases.
Form 8995 or 8995-A: Calculates the qualified business income deduction.
Form 8829: May be required for a home office deduction using the actual-expense method. It is generally not required when using the simplified method.
Don’t want to deal with all that paperwork on your own? File through Keeper. We’ll help you claim all your savings and take care of every form for you, so you can get on with your life.
If you’d rather file your own business taxes, though, read on to make sure you don’t miss out on any savings.
Over 1M Americans trust Keeper for their complex taxes
The #1 tax app for freelancers, gig workers, and self-employed filers.
Get started free
Claim your business write-offs with Schedule C
Here’s where you’ll:
✓ Report your earnings from self-employment
✓ Write off your business expenses to determine your business’s total taxable income
You can learn more about how to fill it out in our complete guide to Schedule C.
If you’re claiming a home office, you might also have to fill out Form 8829.
Deduct half of your self-employment tax on Schedule SE
This form goes hand-in-hand with your Schedule C. Schedule SE is where you’ll:
✓ Calculate your self-employment tax, based on your net profit from Schedule C
✓ Use your self-employment taxes to save on income taxes
Get your QBI deduction on Form 8995
If your 2026 taxable income (before the QBI deduction) is more than $201,750 — or $403,500 if you’re married filing jointly — you’ll use the longer version of the form, Form 8995-A.
Claim your other income tax savings on Schedule 1
On Schedule 1 of your Form 1040 (Part II, Adjustments to Income), you'll claim tax savings on your:
✓ Health insurance
✓ Retirement contributions
There’s no “one weird trick” to dealing with the IRS. But there are definitely plenty of legal methods for avoiding extra taxes on your 1099 income.

Melissa Pedigo has been a CPA for over 20 years and she is one of the only CPA copywriters in the world. With a vast knowledge of U.S. tax and accounting, she’s able to write about tax and finance topics from a unique perspective...as an industry expert. When she’s not writing or being an accounting nerd, you’ll find her watching and playing tennis, reading, tending to her half-grown garden, and studying foreign languages
View full bio
Scott Levy grew up in Miami, Florida, the son of a CPA and Tax Attorney. You could say taxes were in his blood. He's been a licensed CPA since 2011 with a Bachelors in Accounting, and a Master's in Applied Economics and Data Intelligence. Over the years, Scott has worked with a large variety of clients from different walks of life. From bartenders to CEOs, Scott has helped them all maximize their tax savings and plan for their futures.
View full bio2 sources
Keeper’s tax guides are built on primary sources: the tax code, IRS forms, instructions and publications, and state tax agency guidance. We link to external sources where appropriate and check figures against the tax year they apply to. This article was peer reviewed by a licensed tax professional (CPA or EA).
This article is for informational purposes only and isn’t tax, legal, or financial advice. Tax rules change and depend on your situation, so talk to a tax professional about yours.